Showing posts with label Quantitative Easing program (QE). Show all posts

Monday, August 4, 2014

Defining Away Economic Failure

Paul Craig Roberts

Last week’s government guesstimate that second quarter 2014 real GDP growth will be 4% seems nonsensical on its face. There is no evidence of increases in real median family incomes or real consumer credit that would lift the economy from a first quarter decline to 4% growth in the second quarter. Middle class store closings (Sears, Macy’s, J.C. Penney) have spread into the Dollar stores used by those with lower incomes. Family Dollar, a chain in the process of closing hundreds of stores is being bought by Dollar Tree, the only one of the three Dollar store chains that is not in trouble. Wal-Mart’s sales have declined for the past 5 quarters. Declining sales and retail store closings indicate shrinking consumer purchasing power. Retail facts do not support the claim of a 4% GDP growth rate for the second quarter, and they do not support last Friday’s payroll job claim of 26,700 new retail jobs in July.

What about the housing market? Don’t the headlines accompanying last Friday’s payroll jobs report, such as “Hiring Settles Into Steady Gains,” mean more people working and a boost to the economy from a housing recovery? No. What the financial press did not report is that the US is in a structural jobs depression. In the 12-month period from July 2013 through July 2014, 2.3 million Americans of working age were added to the population. Of these 2.3 million only 330 thousand entered the labor force. My interpretation of this is that the job market is so poor that only 14% of the increase in the working age population entered the labor force.

The decline in the labor force participation rate is bad news for the housing market. The US labor force participation rate peaked at 67.3% in 2000 and has been in a sustained downturn ever since. The rate of decline increased in October 2008 with the bank bailout and Quantitative Easing. From October 2008 to the present, 13.2 million Americans were added to the working age population, but only 818 thousand, or 6%, entered the labor force.  Despite government and financial press claims, the Federal Reserve’s multi-year policy of printing money with which to purchase bonds did not restore the housing or job markets.

What about the stock market? It has been down in recent days but is still high historically. Isn’t the stock market evidence of a good economy? Not if stocks are up because corporations are buying back their own stock. Corporations are now the largest buyers of stocks. Recently we learned that from 2006 through 2013 corporations authorized $4.14 trillion in buybacks of their publicly traded stocks. Moreover, it appears that corporations have been borrowing the money from banks with which to buy back their stocks. Last year there were $754.8 billion in authorized stock buybacks and $782.5 billion in corporate borrowing. In the first three months of this year, companies purchased $160 billion of their own stocks.

Borrowing to buyback stock leaves a company with debt but without new investment with which to produce revenues to service the debt. The massive stock buybacks demonstrate that American capitalism is now corrupt. In order to maximize personal short-term financial benefits flowing from bonuses, stock options, and capital gains, CEOs, boards of directors, and shareholders are decapitalizing public companies and loading them up with debt.

Well, isn’t the economy being helped by the return of manufacturing to America? Apparently not. Data for 1999-2012 indicate that the offshoring of manufacturing increased by 9%.

One economist, Susan Hester, an economist for the Retail Industry Leaders Association, has decided to turn the loss of manufacturing jobs into a virtue. Her argument is that retail employment dwarfs manufacturing employment and that more American jobs can be created by selling more imports than by encouraging manufacturing in order to provide exports.

According to Ms. Hester’s research, the US makes more money from the retail side than from the production side. She concludes that the value added to a product by offshore labor is a small percentage of the value added by “managing offshored production, handling Customs clearances, managing warehouses and distribution, marketing apparel products, and by millions of people in the retail sector stocking shelves and working cash registers.”

In other words, the US manufacturing jobs moved offshore are just a throwaway. The money is made in selling the imports.

Ms. Hester neglects to recognize that when offshored production is brought to the US to be marketed, it comes in as imports and results in a larger US trade deficit. Foreigners use dollars paid to them for the products that they make for US firms to purchase ownership of US bonds, stocks, and real assets such as land, buildings, and companies. Consequently, interest, profits, capital gains, and rents associated with the foreign purchases of US assets now flow to foreigners and not to Americans. The current account worsens.

It works like this: The excess of US imports over US exports leaves foreigners with claims on US income and wealth that are settled by foreign purchases of US assets. The income produced by these assets now flows abroad with the consequence that income earned by foreigners on their US investments exceeds the income earned by the US on its foreign investments.

According to Ms. Hester’s reasoning, Americans would be better off it they produced nothing that they need and in place of manufacturing relied on the incomes of US fashion designers and pattern makers who specify the offshored production for US markets, on the compliance officers and freight agents, on production planning and expediting clerks, and on longshore workers and railroad employees who deliver the foreign-made goods to US consumer markets.

Ms. Hester believes that the value-added by offshored manufacturing is inconsequential. How then did China get rich from it, becoming the second largest economy and employing 100 million people in manufacturing (compared to America’s 12 million), and acquire the largest foreign reserves of any country?

After Ms. Hester answers that question she can explain why US corporations go to the trouble to offshore their manufacturing if the contribution to value-added is so low? The value added is obviously substantial enough for the labor cost savings to pay for transportation costs to the US from Asia, for the cost of set-up and management of foreign based facilities, and for the cost of the adverse publicity from abandoning US communities for Asia and still leave value-added after all costs to enlarge profits and drive up stock prices and executive bonuses.

Ms. Hester fools herself. The low value that she calculates Chinese, Indian, or Vietnamese labor adds to the price of a shirt reflects the low foreign labor cost, not a low value of the shirt in US markets or a low value of an iPhone in European markets. Marketing, warehousing and distribution are done in the US by more highly paid people, and this is why it looks like the value added comes from sources other than manufacturing. Ms. Hester overlooks that the lower cost of foreign labor does not translate into a less valued product but into higher profits.

Economists assume that the labor cost savings are passed on to the consumers in lower prices, but I have not experienced declining prices of Nike and Merrell sports shoes, of sheets and towels, of Brooks Brothers and Ralph Lauren shirts, of Apple computers, or whatever as a result of moving US production offshore. The labor cost savings go into profits, managerial bonuses, and capital gains for shareholders and is one reason for the extraordinary increase in income and wealth inequality in the US.

Focused on short-term profit, manufacturers and retailers are destroying the US consumer market. The average annual salary of a US apparel manufacturing worker is $35,000. The average salary of US retail employees is less than half of that amount and provides no discretionary income with which to boost consumer spending in retail stores.

The American corporate practice of offshoring manufacturing has made it impossible for the Obama regime to keep its promises of creating manufacturing jobs and exports. Unable to create real jobs and real exports, the US government has proposed to create virtual jobs and virtual exports made by “factoryless goods producers.” In order to keep his promise of doubling the growth of US exports, the Obama regime wants to redefine foreign output as US output.

A “factoryless goods producer” is a newly invented statistical category. It is a company like Nike or Apple that outsources the production of its products to foreign companies. The Obama regime is proposing to redefine companies such as Apple that own a brand name or a product design as manufacturing companies even though the companies do not manufacture.

In other words, whether or not a US company is a manufacturer does not depend on its activity, but on its ownership of a brand name made for the company by a foreign manufacturer. For example, Apple iPhones made in China and sold in Europe would be reported as US exports of manufactured goods, and iPhones sold in the US would no longer be classified as imports but as US manufacturing output. Apple’s non-manufacturing employees would be transformed into manufacturing employment.

Clearly, the purpose of this statistical deception is to inflate the number of US manufacturing jobs, US manufacturing output, and US exports and to convert imports into domestic production. It is a scheme that eliminates the large US trade deficit by redefinition.

The reclassification would leave the government’s Office of Statistical Lies with the anomaly that products made in China, India, Indonesia or wherever become US GDP as long as the brand name is owned by a US corporation, but the payments to the Asian workers who produced the products remain as claims on US wealth and can be converted into ownership of US bonds, companies, and real estate.

For example, Chinese workers produced the Apple products, and China has the claims on US wealth to prove it. How are these claims accounted for statistically by the Obama regime’s redefinition? The US can add China’s production of the Apple products to US GDP, but how does the US deduct the Chinese-produced Apple products from China’s GDP? And how does the Obama regime’s redefinition get rid of the payments by Apple to the Chinese labor that produced the products? These payments comprise claims on US wealth.

In other words, the reclassification would double count the output of Apple’s products. If every country does this, world GDP will rise statistically regardless of the fact that no more goods and services are produced. Perhaps this is the way to define away world poverty.

“Factoryless goods producers” was foreshadowed by Harvard professor Michael Porter’s 2006 competitiveness report, a justification for jobs offshoring. Defending jobs offshoring, Porter downplayed the rise in the US trade deficit and decline in the US GDP growth rate caused by jobs offshoring. Porter argued, in effect, that ownership of the revenues and products, not the location in which the revenues and products are produced, should determine their classification. As I pointed out in my critique (see The Failure of Laissez Faire Capitalism and Economic Dissolution of the West), the result would be to raise US GDP by the amount of US production outsourced abroad and by the output of US overseas subsidiaries and to decrease the GDP of the countries in which the manufacturing actually takes place. Consistency would require that the German and Japanese autos, for example, that are produced in the US with US labor would become deductions from US GDP and be reported as German and Japanese GDP.

As I have emphasized for years, the West already lives in the dystopia forecast by George Orwell.


Jobs are created by hypothetical add-ons to the reported payroll figures and by inappropriate use of seasonal adjustments. Inflation is erased by substituting lower priced items in the inflation index for those that rise in price and by redefining rising prices as quality improvements. Real GDP growth is magicked into existence by deflating nominal GDP with the understated measure of inflation. Now corporations without factories are going to produce US manufacturing output, US exports, and US manufacturing jobs!

Every sphere of Western existence is defined by propaganda. Consequently, we have reached a perfect state of nihilism. We can believe nothing that we are told by government, corporations, and the presstitute media.

We live in a lie, and the lie is ever expanding.

Thursday, July 10, 2014

The Deteriorating Economic Outlook

July 8, 2014

Paul Craig Roberts, Dave Kranzler, and John Williams

The third and final estimate (until the annual GDP revisions) of first quarter 2014 real GDP growth released June 25 by the US Bureau of Economic Analysis was a 2.9% contraction in GDP growth, a 5.5 percentage point difference from the January forecast of 2.6% growth. Apparently, the first quarter contraction was dismissed by those speculating in equities as weather related, as stock averages rose with the bad news.

Stock market participants might be in for a second quarter surprise. The result of many years of changes made to the official inflation measures is a substantially understated inflation rate. John Williams (www.shadowstats.com) provides inflation estimates based on previous official methodology when the Consumer Price Index still represented the cost of a constant standard of living. The 1.26% inflation measure used to deflate first quarter nominal GDP is unrealistic, as Americans who make purchases are aware.

A reasonable correction to the understated deflator gives a much higher first quarter contraction. The two main causes of inflation’s understatement are the substitution principle introduced during the Clinton regime and the hedonic adjustments ongoing since the 1980s that redefine price rises as quality improvements. Correcting for excessive hedonic adjustments gives a first quarter real GDP contraction of 5%. Correcting for hedonic and substitution adjustments gives a first quarter real GDP contraction of 8.5%.

Realistic economic analysis is a rarity. The financial press echoes Wall Street, and Wall Street economists are paid to help sell financial instruments. Gloomy analysis is frowned upon. Even negative quarters are given a positive spin.

Years of understatement of inflation has resulted in years of overstatement of GDP growth. Thinking about the many years of misstatement, we realized that the typical computation in nominal terms of the ratio of debt to GDP is seriously misleading.

Consider that debt is issued in nominal terms and repaid in nominal terms (except for a few Treasury bonds with inflation adjustments). However, nominal wealth or nominal GDP overstates real economic strength. The debt is growing, but both the nominal and real values of the output of goods and services are not keeping up with the rise in debt.

To understand how risky the rise of debt is, nominal debt must be compared to real GDP. Spin masters might dismiss this computation as comparing apples to oranges, but such a charge constitutes denial that the ratio of nominal debt to nominal GDP understates the wealth dilution caused by the government’s ability to issue and repay debt in nominal dollars. We know that inflation favors debtors, because debts can be repaid in inflated dollars.

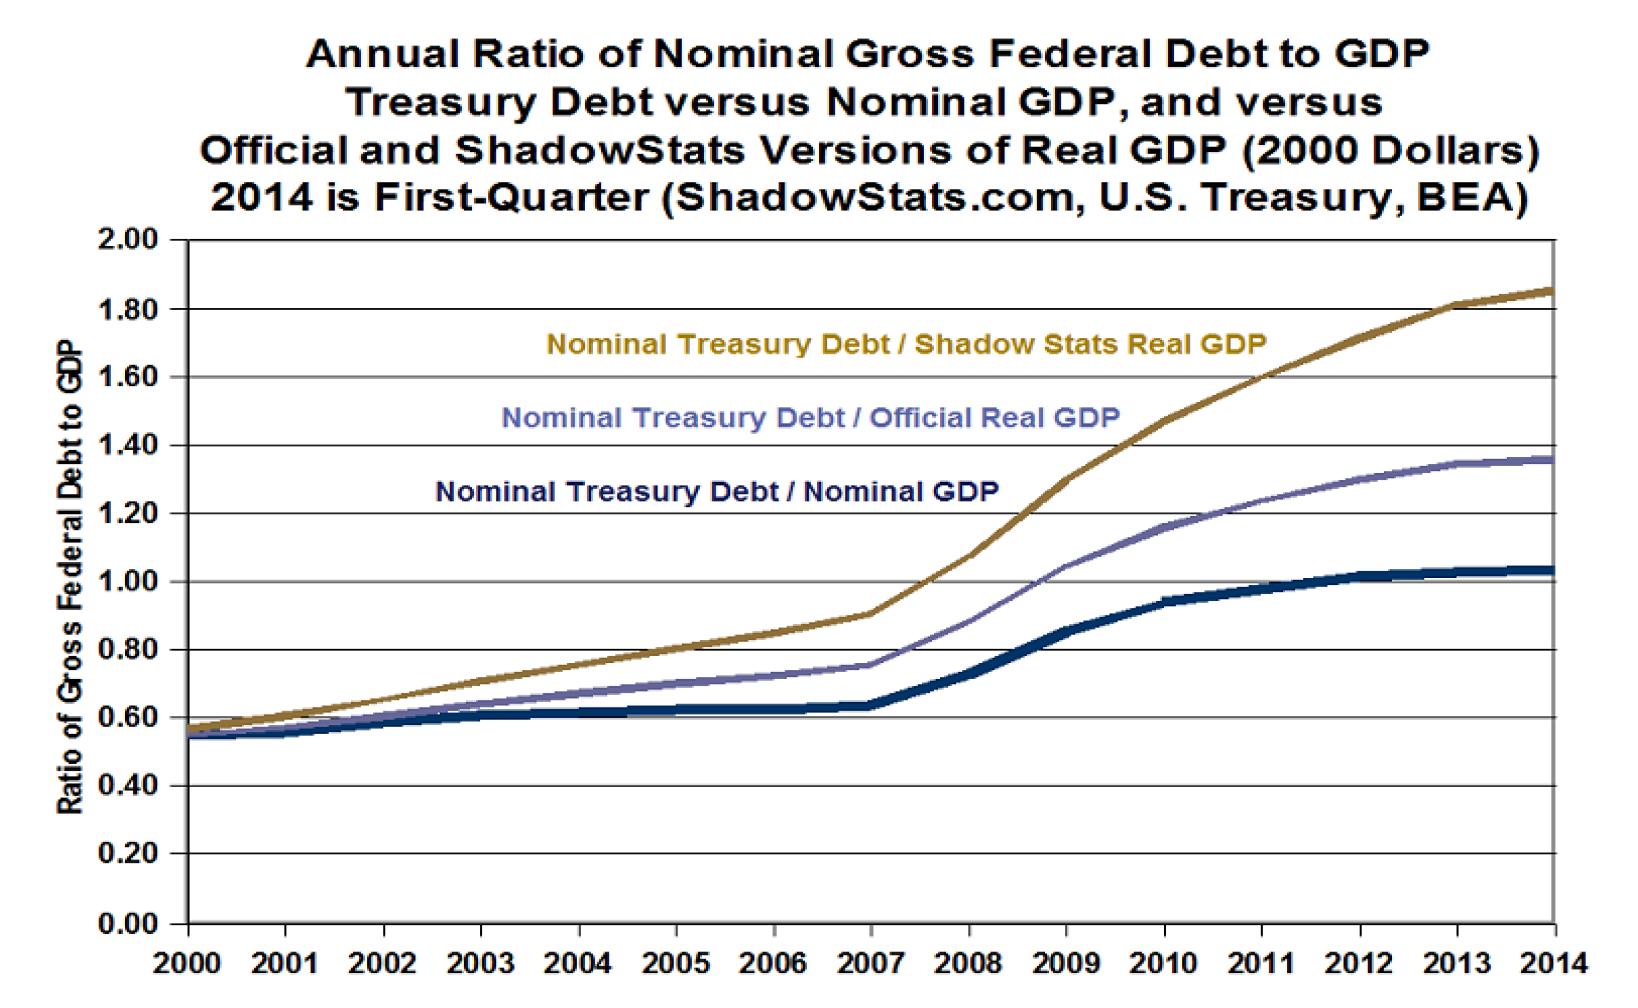
The graph below shows three different debt to GDP ratios. The bottom line is nominal debt to nominal GDP, the financial press ratio. The middle line is the ratio of nominal debt to the official measure of real GDP. The top line is the ratio of nominal GDP to Shadowstats’ corrected measure of real GDP that puts back in some of the inflation that is no longer included in official measures. The basis for this corrected measure is also 2000, but as the GDP number for 2000 is lower due to correction, this graph begins with the ratio at a slightly higher point.


The nominal debt to GDP ratio shows that as of the end of the first quarter of 2014 total US Treasury debt outstanding is 103 percent of US GDP.

The ratio of Treasury debt to official real GDP shows debt at 136% of GDP.

The ratio of debt to real GDP deflated with more a more realistic measure of inflation, one more in keeping with the experience of consumers, puts US public debt at 185% of GDP. In other words, the burden of US debt on the real economy is almost twice the burden that is normally perceived.

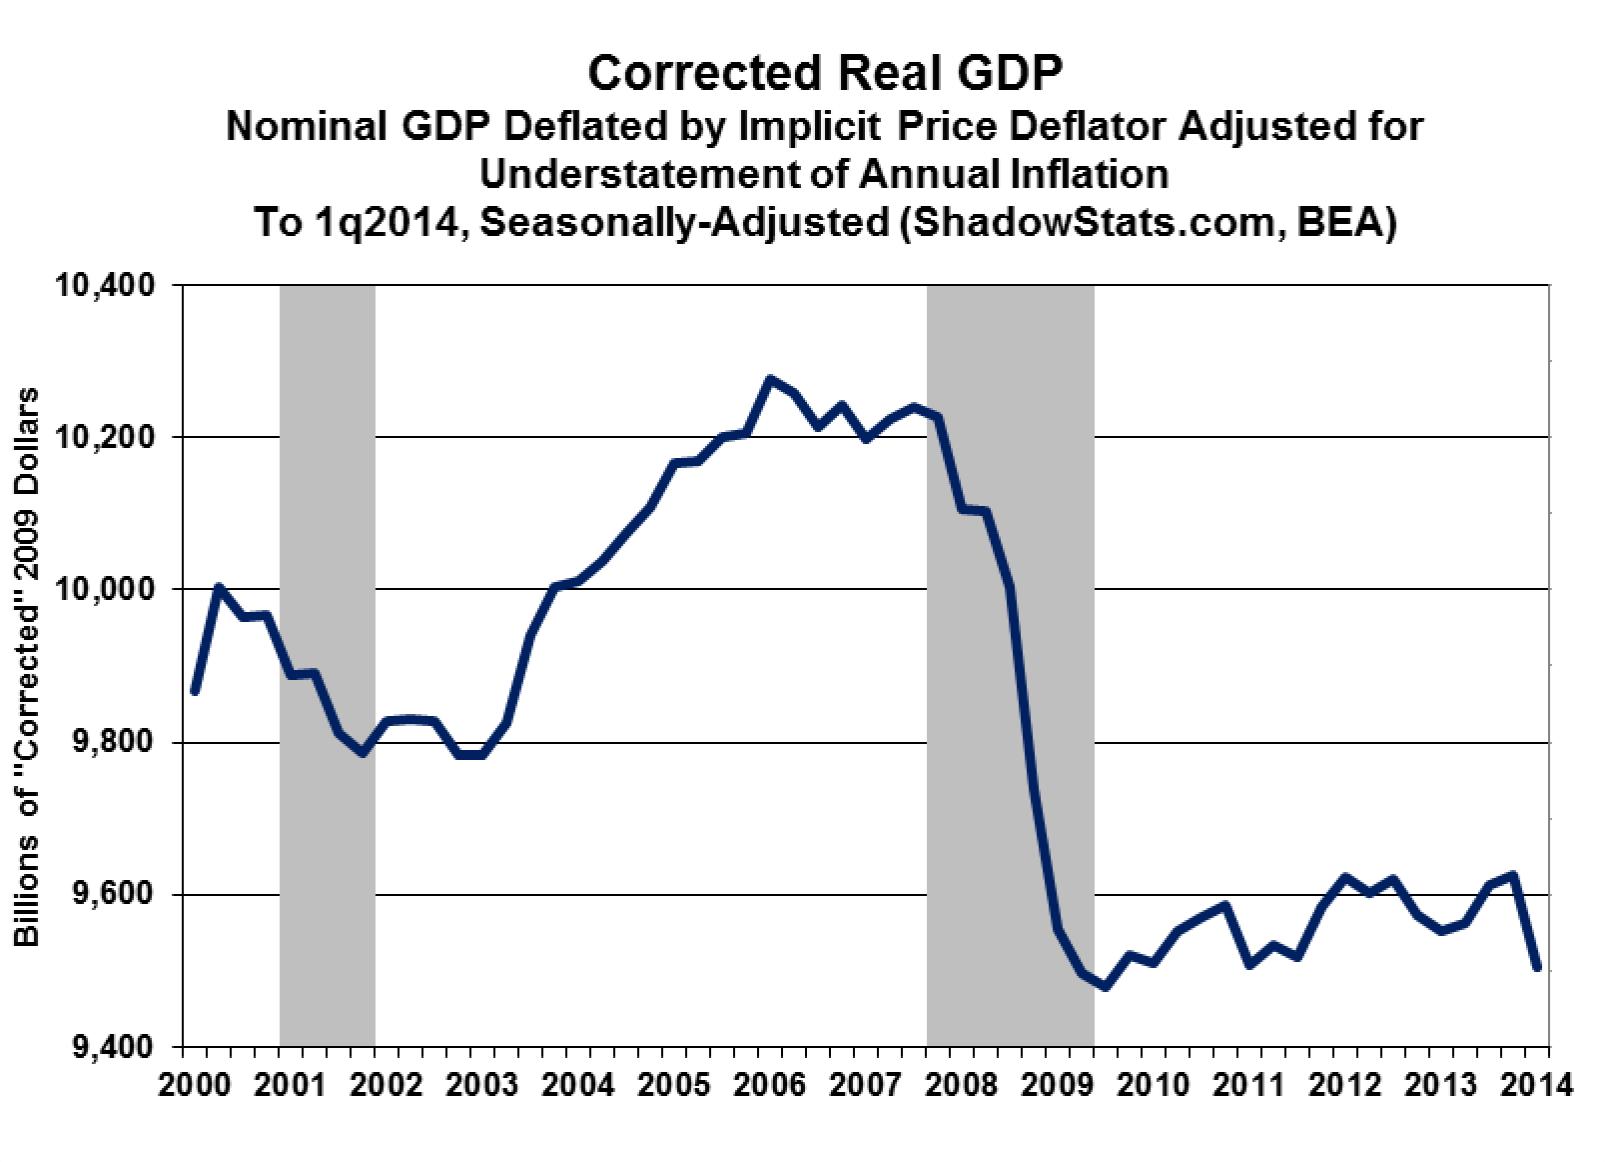
The Shadowstats adjustment we made to real GDP does not fully correct for what we believe has been a growing understatement of inflation since the 1980s. The adjustment we made corrects the implicit price deflator for a two-percentage point understatement of annual inflation due to hedonic distortion. Real GDP with this correction since 2000 looks like this:


We have calculated the ratios of US public debt to nominal GDP and to two measures of real GDP. The ratios of debt to GDP would be much higher if we used total credit outstanding, or total public and private debt, and if we used the government’s unfunded liabilities. The fact seems clear that debt is a major and unappreciated issue for the US economy. The enormous debt, especially with the middle class economy largely offshored, implies substantially lower living standards for the 99 percent.

The first quarter contraction, especially our corrected number, implies a second quarter negative real GDP. In other words, the years of Quantitative Easing (money printing) by the Federal Reserve has not resulted in economic recovery from the 2008 downturn and has not prevented further contraction.

Massive money creation and huge fiscal deficits have protected the balance sheets of “banks too big to fail” but have harmed the American people. Retirees and pension funds have been deprived for years of interest income as the Federal Reserve engineered zero or negative interest rates for the sake of a handful of oversized banks.

The extraordinary creation of new dollars diluted the dollars held by peoples, companies, institutions, and central banks throughout the world, raising fears that the dollar would lose exchange value and its role as world reserve currency.

Washington’s use of financial sanctions to force other countries to bend to Washington’s will is causing countries to leave the dollar payments system. Russian President Vladimir Putin’s advisor has said that the dollar must be crashed as the only way to prevent US aggression. The Chinese have called for “de-americanizing the world.”

The imperialistic US Foreign Account Tax Compliance Act (FATCA), which comes into full force July 1, 2015, imposes such heavy reporting costs on foreign financial institutions that these institutions might opt out of dollar transactions. All together, the result could be a serious tumble in the value of the US dollar, more wealth contraction, higher inflation via import prices, and less US wealth available to support US debt.

In view of this reality, why is Washington pushing its puppet in Kiev toward war with Russia? Why is Washington pushing NATO to spend more money and build more bases on which to deploy more troops in the Baltics and Eastern Europe, especially when Washington’s contribution will be the largest part of the cost? Why is Washington re-entering the Middle East conflict that Washington began by inciting Sunni and Shia against one another? Why is Washington constructing new naval and air bases from the Philippines to Vietnam in order to encircle China?

If Washington is this unaware of its budget constraints and its financial predicament, it cannot be long before Americans experience economic catastrophe.

Monday, May 5, 2014

US Economy Is A House Of Cards

Paul Craig Roberts

The US economy is a house of cards. Every aspect of it is fraudulent, and the illusion of recovery is created with fraudulent statistics.

American capitalism itself is an illusion. All financial markets are rigged. Massive liquidity poured into financial markets by the Federal Reserve’s Quantitative Easing inflates stock and bond prices and drives interest rates, which are supposed to be a measure of the cost of capital, to zero or negative, with the implication that capital is so abundant that its cost is zero and can be had for free. Large enterprises, such as mega-banks and auto manufacturers, that go bankrupt are not permitted to fail. Instead, public debt and money creation are used to cover private losses and keep corporations “too big to fail” afloat at the expense not of shareholders but of people who do not own the shares of the corporations.

Profits are no longer a measure that social welfare is being served by capitalism’s efficient use of resources when profits are achieved by substituting cheaper foreign labor for domestic labor, with resultant decline in consumer purchasing power and rise in income and wealth inequality. In the 21st century, the era of jobs offshoring, the US has experienced an unprecedented explosion in income and wealth inequality. I have made reference to this hard evidence of the failure of capitalism to provide for the social welfare in the traditional economic sense in my book, The Failure of Laissez Faire Capitalism, and Thomas Piketty’s just published book, Capital in the 21st Century, has brought an alarming picture of reality to insouciant economists, such as Paul Krugman. As worrisome as Piketty’s picture is of inequality, I agree with Michael Hudson that the situation is worse than Piketty describes. http://michael-hudson.com/2014/04/pikettys-wealth-gap-wake-up/

Capitalism has been transformed by powerful private interests whose control over governments, courts, and regulatory agencies has turned capitalism into a looting mechanism. Wall Street no longer performs any positive function. Wall Street is a looting mechanism, a deadweight loss to society. Wall Street makes profits by front-running trades with fast computers, by selling fraudulent financial instruments that it is betting against as investment grade securities, by leveraging equity to unprecedented heights, making bets that cannot be covered, and by rigging all commodity markets.

The Federal Reserve and the US Treasury’s “Plunge Protection Team” aid the looting by supporting the stock market with purchases of stock futures, and protect the dollar from the extraordinary money-printing by selling naked shorts into the Comex gold futures market.

The US economy no longer is based on education, hard work, free market prices and the accountability that real free markets impose. Instead, the US economy is based on manipulation of prices, speculative control of commodities, support of the dollar by Washington’s puppet states, manipulated and falsified official statistics, propaganda from the financial media, and inertia by countries, such as Russia and China, who are directly harmed, both economically and politically, by the dollar payments system.

As the governments in most of the rest of the world are incompetent, Washington’s incompetence doesn’t stand out, and this is Washington’s salvation.

But it is not a salvation for Americans who live under Washington’s rule. As all statistical evidence makes completely clear, the share of income and wealth going to the bulk of the US population is declining. This decline means the end of the consumer market that has been the mainstay of the US economy. Now that the mega-rich have even more disproportionate shares of the income and wealth, what happens to an economy based on selling imports and off-shored production of goods and services to a domestic consumer market? How do the vast majority of Americans purchase more when their incomes have not grown for years and have even declined and they are too impoverished to borrow more from banks that won’t lend?

The America in which I grew up was self-sufficient. Foreign trade was a small part of the economy. When I was Assistant Secretary of the Treasury, the US still had a trade surplus except for oil. Offshoring of America’s jobs had not begun, and US earnings on its foreign investments exceeded foreign earnings on US investments. Therefore, America’s earnings abroad covered its energy deficit in its balance of trade.

The economic stability achieved during the Reagan administration was shattered by Wall Street greed. Wall Street threatened corporations with takeovers if the corporations did not produce higher profits by relocating their production of goods and services for American markets abroad. The lower labor costs boosted earnings and stock prices and satisfied Wall Street’s cravings for ever more earnings, but brought an end to the rise in US living standards except for the mega-rich. Financial deregulation loaded the economy with the risks of asset bubbles.

Americans are an amazingly insouciant people. By now any other people would have burnt Wall Street to the ground.

Washington has unique subjects. Americans will take endless abuse and blame some outside government for their predicament–Iraq, Afghanistan, Libya, China, Russia. Such an insouciant and passive people are ideal targets for looting, and their economy, hollowed-out by looting, is a house of cards.

Thursday, February 6, 2014

A Clear and Present Danger to Financial Stability

The Fed's Taper Sends Global Shares and Emerging Markets Tumbling
by MIKE WHITNEY


The selloff that began in May 2013, when the Fed announced its plan to scale back its asset purchases, resumed with a vengeance on Monday as global shares were slammed in heavy trading sending the Dow Jones for a 326 point-loss on the day. The proximate cause of the rout was a worse-than-expected manufacturing report and sluggish construction spending, but the underlying source of the trouble was the Fed’s decision to wind down QE which, according to Bloomberg news, “helped drive the S and P 500 up 157 percent from a 12-year low in 2009.” The Fed’s tightening has reversed the dynamic that pushed equities into the stratosphere and generated an unprecedented boom in the emerging markets. Now capital is fleeing the EMs to the safety of US Treasuries while jittery investors ditch stocks and wait to see if the storm passes or gradually gains strength.

The mood on Wall Street has turned bearish overnight as markets in Europe and Asia continue to hemorrhage led by another bloodletting on Japan’s Nikkei which has slumped by a full a 14 percent since its Dec. 30 peak. Societe Generale’s emerging market strategist, Benoit Anne, summed up the mood in a terse note to her clients saying, “There is no point spending too much time trying to pick and choose when faced with a severe market crisis like the one we are witnessing in front of our screens. Right now, sell everything.”

Markets have entered a new phase in the ongoing financial crisis, a crisis which originated on Wall Street where trillions of dollars of fraudulently-manufactured “toxic” assets were produced by a criminal bank cartel and sold to unsuspecting investors around the world. Rather than write down the losses and restructure the banking system, policymakers at the Central Bank and US Treasury opted to conceal the damage with massive bailouts, financial repression, zero rates and regular infusions of liquidity, all of which helped to hide the rot at the heart of the system. The Fed’s plan to taper has removed the veil and exposed the weakness of an undercapitalized system that has been made more unstable by 5 years of misguided policy. This is real source of the problem.

Just as the Fed’s uber-accommodationist policy lifted stocks to record highs in the months preceding its taper announcement, so too, the withdrawal of central bank support is likely to increase the pace of the decline. That is why we expect the taper to be implemented in a stutter-step manner, stopping and starting sporadically depending on conditions in the market. Naturally, this will undermine the Fed’s attempts to send investors a clear message about the direction of policy. It also means that new Fed chairman Janet Yellen is going to spend less time trying to maintain the Fed’s mandate of “price stability and full employment” then simply putting out fires. Here’s a clip from Naked Capitalism with some background on the turmoil:
“Since Bernanke started talking about “tapering off” Quantitative Easing, the bond markets have freaked out. This is a very logical reaction….Bernanke and other Federal Reserve economists appear bewildered by this phenomenon. The impression one gets from their follow-up comments is that they wished they could ask bond speculators “did you read the damn speech?” The answer, of course, is no and for good reason.

All investors need to know is the conditions under which QE … will be pursued has changed. Now the substantive change may actually be relatively minor, but that’s irrelevant to speculators. The reason is very simple: those holding assets with longer maturities will take huge capital losses with relatively small changes in interest rates ……It is better to exit now when those future changes are uncertain then take even more massive losses.” (“Market rout continues, proving abject failure of Fed’s forecasts and policies”, Naked Capitalism)

This is the logic of selling early even though the reduction of asset purchases is still in its opening phase. There’s no sense in waiting until the last minute and taking a chance of getting trampled in the stampede to the exits. Just cash in and relax.

The Fed’s trillion cash injections have created a fantasy world of ever-rising stock prices that’s gradually giving way to the emerging reality of dismal earnings, chronic-high unemployment, droopy incomes, stagnant wages, swollen P/E ratios and a bloated financial sector that requires a larger and larger share of the nation’s wealth to avoid another devastating collapse. This is the situation we find ourselves in today, a situation that is papered over with propaganda about meaningless data points that fail to identify the real source of the problem, which is the gigantic capital hole created by the toxic assets that have not yet been written down, but are still sucking the life out of the bedraggled economy via debt servicing, rate and liquidity subsidies, and the reshaping of economic policy to preserve zombie institutions which need to be euthanized.

The problem is not hard to grasp, in fact, most people will understand what’s going on by just reading this two-paragraph excerpt from an article which appeared in Forbes magazine back in February, 2009. Here’s a clip from the piece titled “Zombie Firms and Zombie Banks”:
”Beginning in 1991, Japan experienced a financial crisis that has been documented and studied by many. Japan’s crisis was triggered by a real estate and equity price bubble followed by a collapse of equity and real estate prices. But unlike the examples I cited above, Japanese policymakers met the crisis with prolonged denial and then, when conditions forced recognition of the severity of the problem, very halting steps to address it. Banks were not forced to recognize the condition of their balance sheets and were encouraged to continue lending to firms that were themselves unprofitable. Anil Kashyap labels these “zombie firms.”

Zombie banks continued to direct capital to zombie firms. This charade continued for more than a decade, with the result that the once-powerful Japanese economy was completely stagnant for that period. The government’s main response was to dramatically increase spending on infrastructure and frantically try to get Japanese households to save less and consume more. The resulting “lost decade” of economic growth cost Japan more than 20% of GDP.” (“Zombie Firms And Zombie Banks”, Thomas F. Cooley, Forbes)

Sound familiar? This same phenom is playing out in the US today. The Fed has spared no expense to perpetuate the illusion that the zombie banking system is solvent and that the trillions of dollars in losses from worthless assets has somehow vanished into thin air. But they haven’t vanished. They are either hidden-away via accounting trickery, passed off to gullible, yield-crazed investors, or transferred onto the Fed’s bulging balance sheet. In any event, the debts are real, they’re impeding the recovery, they’re sucking the life’s blood out of the economy, and they’re clear and present danger to financial stability.

The red ink has to be purged, just as the rickety, Potemkin banking system has to be put out of its misery. We need a fresh start.

Tuesday, February 4, 2014

Prelude to a Crash

Margin Debt Hits All-Time High in December
by MIKE WHITNEY

The Fed’s easy money policies have pushed margin debt on the New York Stock Exchange (NYSE) to record levels laying the groundwork for a severe correction or another violent market crash.

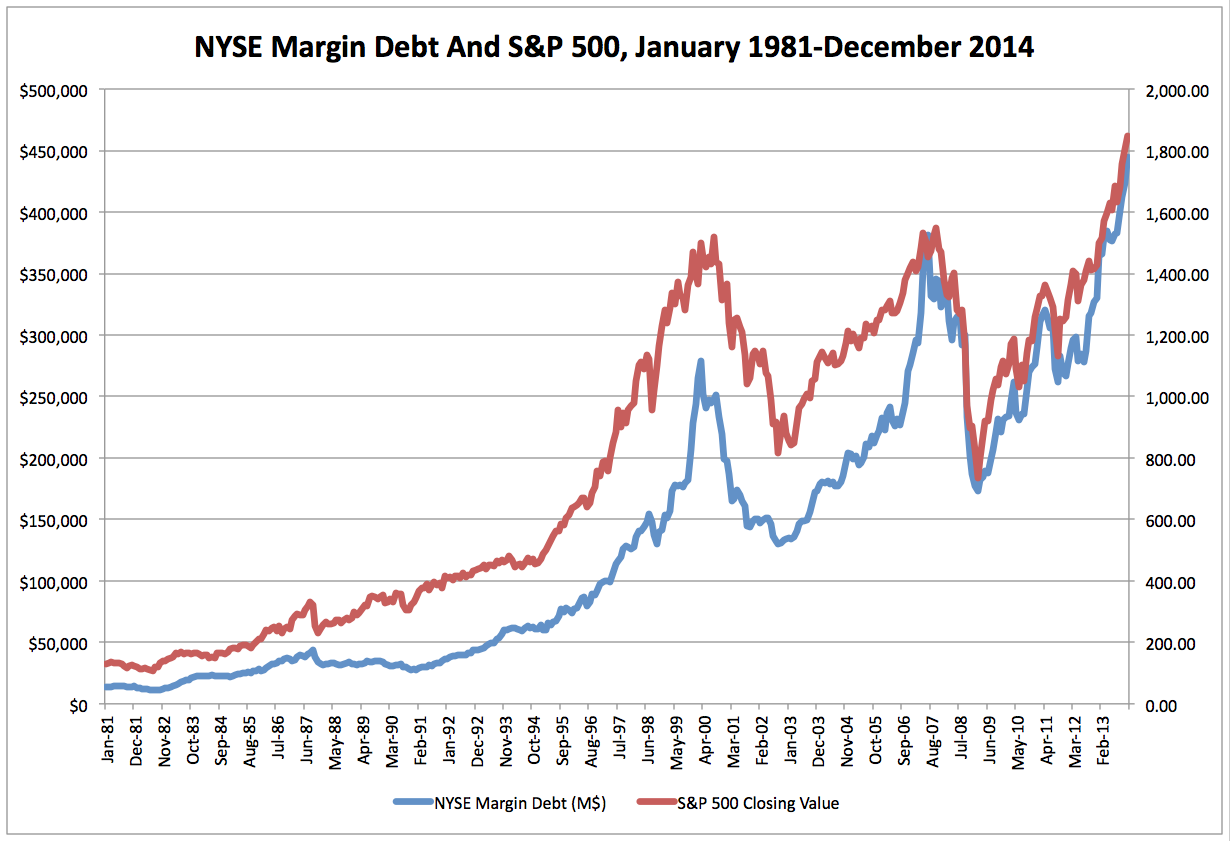
In December, margin debt rose by $21 billion to an all-time high of $445 billion.

Buying equities on margin, that is, with loads of borrowed cash, is a sign of excessive risk taking the likes of which invariably takes place whenever the Central Bank creates subsidies for speculation by keeping interest rates pegged below the rate of inflation or by pumping trillions of dollars into the bloated financial system through misguided liquidity programs like QE.

Investors have shrugged off dismal earnings reports, abnormally-high unemployment, flagging demand, droopy incomes, stagnant wages and swollen P/E ratios and loaded up on stocks confident that the Fed’s infusions of liquidity will keep prices going higher. It’s only a matter of time before they see the mistake they’ve made.

The chart below illustrates how zero rates and QE lead to excessive risk taking. The correlation between the stratospheric rise of margin debt and the Fed’s destabilizing monetary policy is hard to avoid. This is what bubblemaking looks like in real time.


Chart: Seeking Alpha.

In the minutes of the FOMC’s December meeting, FOMC officials acknowledge the froth they’ve created in financial assets which is why they’ve begun to scale back their asset purchases. The Fed hopes that by gradually winding down QE they’ll be able to stage a soft landing rather than a full-blown crash. Here’s an excerpt from the FOMC’s minutes:
“In their discussion of potential risks, several participants commented on the rise in forward price-to-earnings ratios for some smallcap stocks, the increased level of equity repurchases, or the rise in margin credit. One pointed to the increase in issuance of leveraged loans this year and the apparent decline in the average quality of such loans.”

There you have it, the Fed sees the results of its work; the distortions in P/E ratios, the exuberant stock buybacks (“equity repurchases”), the deterioration in the quality of leveraged loans, and the steady rise in margin debt. They see it all, all the bubbles they’ve created with their gargantuan $3 trillion surge of liquidity. Now they have started to reverse the policy by reducing their asset purchase from $85 bil to $65 bil per month, the effects of which can already be seen in the Emerging Markets.

The bubble in Emerging Markets has burst sending foreign currencies plunging and triggering a sharp reversal in capital flows. The hot money that flooded the EMs,–(which lowered the cost of borrowing for businesses and consumers)–is entirely attributable to the Fed’s policy. QE pushes down long-term interest rates forcing investors to search for higher yield in other markets. Thus, the cost of money drops in EMs creating a boom that abruptly ends when the policy changes (as it has).

Capital is fleeing EMs at an unprecedented pace precipitating a dramatic slowdown in economic activity, higher consumer prices and widespread public distress. The Fed is 100% responsible for the turmoil in emerging markets, a fact which even mainstream news outlets blandly admit. Here’s an excerpt from an article in Bloomberg just this week:
“Investors are pulling money from exchange-traded funds that track emerging markets at the fastest rate on record…More than $7 billion flowed from ETFs investing in developing-nation assets in January, the most since the securities were created, data compiled by Bloomberg show…

Emerging economies have benefited from cheap money as three rounds of Fed bond buying pushed capital into their borders in search of higher returns…

The Fed’s asset purchases had helped fuel a credit boom in developing nations from Turkey to Brazil. Accumulated capital inflows to developing-country’s debt markets since 2008 reached $1.1 trillion, or $470 billion more than their long-term trend, according to a study by the International Monetary Fund in October.” (“Record Cash Leaves Emerging Market ETFs on Lira Drop“, Bloomberg)

The Fed doesn’t care if other countries are hurt by its policies. What the Fed worries about is how the taper is going to effect Wall Street. If the slightest reduction in asset purchases causes this much turbulence abroad, then what’s it going to do to US stock and bond markets?

The answer, of course, is that stocks are going to fall…hard. It can’t be avoided. And while the amount of margin debt is not a reliable tool for calling a top; it’s safe to say that the recent spike in investor leverage has moved the arrow well into the red zone. Investors are going to cash out long before the Fed ends QE altogether, which means the selloff could persist for some time to come much like after the dot.com bubble popped and stocks drifted lower for a full year. Now check out this clip from Alhambra Investment Partners newsletter titled “The Year of Leverage”:
“For the year, total margin debt usage jumped by an almost incomprehensible $123 billion, while cash balances declined by $19 billion. That $142 billion leveraged bet on stocks far surpasses any twelve month period in history. The only times that were even close to as leveraged were the year leading up to June 2007 (-$89 billion) and the twelve months preceding February and March 2000 (-$77 billion). Both of those marked significant tops in the market.” ( Alhambra Investment Partners newsletter titled The Year of Leverage)

Repeat: “The $142 billion leveraged bet on stocks far surpasses any twelve month period in history.” 

Investors are “all-in” because they think that the Fed has their back. They think that Bernanke (or Yellen) will not allow stocks to fall too far without intervening. (This is called the “Bernanke Put”) So far, that’s been a winning strategy, but that might be changing. The Fed’s determination to taper suggests that it wants to withdraw its stimulus to avoid being blamed for the bursting bubble. (“Plausible deniability”?) That’s what’s driving the current policy. Here’s more on margin debt from Wolf Richter at Testosterone Pit:
“On the New York Stock Exchange, margin credit has been hitting new records for months. All three mega-crashes in my investing lifetime have been accompanied by record-setting peaks in margin debt. In September 1987, a month before the crash, margin credit peaked at 0.88% of GDP. In March 2000, when the crash began, margin credit peaked at 2.7% of GDP. In July 2007, three months before the downdraft started, margin credit peaked at 2.6% of GDP. Now, margin credit has already reached 2.5% of GDP.” (“Plagued By Indigestion, Fed Issues Asset-Bubble Warning”, Testosterone Pit)

Stock market crashes are always connected to massive leverage, loosey-goosey monetary policy and irrational exuberance (“excessive risk taking”), the toxic combo that presently rules the markets. The Federal Reserve is invariably the source of all bubblemaking and financial instability.

As we noted earlier, equity repurchases or stock buybacks are another sign of froth. Here’s an excellent summary on the topic by Alhambra Investment Partners:
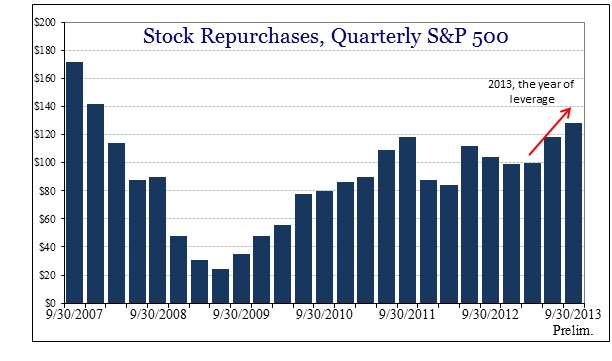
“In the third quarter of 2013, share repurchases totaled $128.2 billion, the highest level since Q4 2007. For the twelve months ended in September 2013, aggregate share repurchases were an astounding $445.3 billion; the only twelve-month period greater than that total was the calendar year of 2007 and its $589 billion.

The common argument advanced in favor of such share repurchases is that companies are using cash to recognize undervalued stocks, but that is total hogwash…

…corporate managers are no different than the reviled stereotypical retail investor. Both leverage themselves further and further as the market goes higher, not in recognizing undervalued stocks or companies but in full froth of chasing obscene values via rationalizations.” ( Alhambra Investment Partners newsletter titled “The Year of Leverage”)


In other words, corporate managers are doing the same thing as your average margin investor. They are loading up on financial assets–not because they think they are a good value or because they expect higher earnings –but because Fed policy supports artificially-high prices. That’s what’s driving the bull market, the Fed’s thumb on the scale. Remove the thumb, and you have a whole new ballgame (as we see in the EMs). There’s also a bubble in high yield “junk” bonds which just had their second biggest year on record (Total issuance $324 billion) Investors are only too happy to dump their money into high-risk debt believing that companies never default or that the Fed will save the day again credit tightens and the dominoes start tumbling through the debt markets. According to Testosterone Pit:

“The cost of a high-yield bond on an absolute coupon basis is as low as it’s ever been,” explained Baratta, king of Blackstone’s $53 billion in private equity assets. Even the riskiest companies are selling the riskiest bonds at low yields… Why would anyone buy this crap?” (“Bubble Trouble: Record Junk Bond Issuance, A Barrage Of IPOs, “Out Of Whack” Valuations, And Grim Earnings Growth”, Testosterone Pit)

Why, indeed? Of course, the author is just being rhetorical, after all, he knows why people are piling into junk. It’s because the Fed has kept a gun to their heads for 5 years, forcing them to grab higher yield wherever they can find it. That’s how Bernanke’s dogwhistle monetary policy works. By slashing rates to zero, the Fed coerces investors to speculate on any type of garbage that’s available. That why junk “just had its second biggest year on record.” You can thank Bernanke.

Housing is also in a bubble due to the Fed’s zero rates, withheld inventory, government modification programs, and an unprecedented uptick in all-cash investors. Clearly, there’s never been a market more manipulated than housing. It’s a joke.

The surge of Wall Street liquidity has spilled over into housing distorting prices and reducing the number of firsttime homebuyers to an all-time low. The homeownership rate is actually falling even while prices climb higher, which is just one of many anomalies created by the Fed’s policy. (Who’s ever heard of a housing boom, where the number of firsttime homebuyers is dropping?)

Also, the Central Bank has purchased more than $1 trillion in mortgage-backed securities (MBS) via QE, which begs the question: How can housing prices NOT be in a bubble?

As we noted earlier, the Fed understands the impact its policies have had. They know the markets are overheated and they’re determined to do something about it. A recent article in Bloomberg explains the Fed’s plan for winding down QE “without doing damage to the economy”. Here’s a short excerpt from the piece:
“Janet Yellen probably will confront a test during her tenure as Federal Reserve chairman that both of her predecessors flunked: defusing asset bubbles without doing damage to the economy…

Yellen is ‘going to be trying to do something that no one has ever done,’ said Stephen Cecchetti, former economic adviser for the Bank for International Settlements, the Basel, Switzerland-based central bank for monetary authorities. She needs ‘to ensure that accommodative monetary policy doesn’t create significant financial stability risks,’ he said in an interview…

The Fed’s ‘first, second and third lines of defense” for dealing with such imbalances is to rely on supervision, regulation and so-called macro-prudential policies, such as mortgage loan-to-value restrictions, Bernanke told the Brookings Institution in Washington on Jan. 16. ….Only as a last resort would it consider raising interest rates.’ (“Yellen Faces Test Bernanke Failed: Ease Bubbles“, Bloomberg)

You got that?

So the Fed is going into the “bubble-deflating” biz.

Check.

And uber-dove Yellen is going to put things right. She’s going to eliminate the price distortions and gradually return the markets to normalcy.

Right, again.

She’s going to wind down QE and start to reduce the Fed’s $4 trillion balance sheet.

Oakie dokie.

And she’s going to do all of this without raising interest rates or sending stocks into freefall?

Right. It’s a pipedream. The first sign of trouble and old Yellen will be scuttling across the floor of the New York Stock Exchange with a punch bowl the size of Yankee Stadium.

You can bet on it.

Sunday, January 5, 2014

Did Someone Say “Crash”?

America's Missing Investors
by MIKE WHITNEY


Guess who’s investing in America’s future?

Nobody, that’s who.

Just check out this excerpt from an article by Rex Nutting at Marketwatch and you’ll see what I mean. The article is titled “No one is investing in tomorrow’s economy”:
“The U.S. economy simply isn’t investing enough to ensure that there will be enough good paying jobs for our children and our children’s children. Net investment — the amount of capital added to our stock — remains at the lowest levels since the Great Depression. …

Net investment…measures the additional stock of buildings, factories, houses, equipment, software, and research and development — above and beyond the replacement of worn-out capital. In 2012, net fixed investment totaled $485 billion, only about half of the $1.1 trillion invested in 2006…

If businesses, consumers and governments were investing for the future at usual rate, the economy would be at least 3% larger, employing millions more people. That’s a huge hole in the economy that can’t be filled by heavily indebted consumers, especially at a time when government is handcuffed by forces of austerity.” (“No one is investing in tomorrow’s economy”, Rex Nutting, Marketwatch)

Now the author seems to believe that the lack of net investment is just a temporary phenom that will work itself out in the years ahead. But he could be wrong about that. After all, why would a company build up its capital stock for the future when the future is so uncertain? Certainly, there’s nothing in the data that would suggest that the US economy is about to shake off its five year post-recession funk and shift into high-gear again, is there? No, of course not. In fact, it looks like the economy has reset at a lower level of activity that will only get worse as the impact of budget cuts and stagnation are felt. That will further curtail consumer spending which, to this point, had been the primary driver of growth.

Bottom line: Net investment is down because there’s no demand. And there’s no demand because unemployment is high, wages are flat, incomes are falling, and households are still digging out from the Crash of ’08. At the same time, the US Congress and Team Obama continue to slash public spending wherever possible which is further dampening activity and perpetuating the low-growth, weak demand, perma-slump.

So, tell me: Why would a businessman invest in an economy where people are too broke to buy his products? He’d be better off issuing dividends to his shareholders or buying back shares in his own company to push stock prices higher.

And, guess what? That’s exactly what CEOs are doing. Check this out in the Washington Post:
“Battered by months of dis­appointing sales, networking giant Cisco needed a way to give its shareholders a pick-me-up. So the San Jose-based firm did what has become routine for many big U.S. companies in a slow-growing economy: It announced last month that it was buying back shares of its stock…..

This is what U.S. multinationals do now with their cash. Rather than tout big new investments, raise worker wages or hire more employees, companies are more likely to set aside funds to reward shareholders — a trend that took a dip during the recession but has roared back during the recovery.

The 30 companies listed on the Dow Jones industrial average have authorized $211 billion in buybacks in 2013, according to data from ­Birinyi Associates, helping to lift the benchmark stock index to heights not seen since the tech boom of the late 1990s. By comparison, the amount is nearly three times what the group spent on research and development last year, according to data from S&P Capital IQ.

Why spend so much on stock repurchasing?

When the number of shares outstanding falls, the value of each one goes up, instantly rewarding shareholders.” (“Companies turning again to stock buybacks to reward shareholders”, Washington Post)

Corporations don’t care about the future. What they care about is maximizing shareholder value, that’s the name of the game; profits. If that means boosting net fixed investment then, okay, that’s what they’ll do. But if the Fed creates incentives to do something else, like gaming the system with stock buybacks, then they can make the adjustment. And that’s what the Fed’s zero rate policy does. It’s incentivizes businesses to use their capital in a way that’s damaging to the real economy. Here’s more from the same article:
“Helping to fuel the stock market’s meteoric rise is the Federal Reserve’s stimulus program designed to lower borrowing costs. Companies are taking advantage, often by borrowing money at low rates to repurchase shares, although it’s unclear how much of the debt is being used to pay for buybacks.

“It somehow feels scarier if they borrowed the money to buy back stock than if they had some investment opportunities,” Inker said. “That somehow seems more sustainable than just levering up to reduce the share count.”

Some analysts say companies are better off repurchasing shares than pouring money into investments promising dubious payoffs, especially in a slow-growing economy.” (“Companies turning again to stock buybacks to reward shareholders”, Washington Post)

There you have it; instead of investing in R&D, factories or new technologies, (all of which produce more high-paying jobs) companies are taking advantage of the Fed’s cheap money, goosing stock prices and raking in hefty profits. That’s just the way the policy works. The only way change the outcome, is to change the incentives. But the Fed doesn’t want to do that, and neither does the Congress because, at present, they have working people right where they want them, under their bootheel.

If you are looking for proof that workers are getting shafted, just look at the condition of the US consumer who is still on the ropes 5 years after the recession ended. Now, according to the latest Fed’s Flow of Funds report, “Household net worth rose by $1.9 trillion in the last quarter” which means that everything should be hunky dory, right? It means the long period of deleveraging should be over and consumers should be ready to go on another madcap spending spree like they did up-until 2007. Unfortunately, the Fed’s report is a bunch of baloney. The $1.9 trillion merely accounts for rising asset prices that have been reflated by Bernanke’s quantitative easing boondoggle. While working people have seen some uptick in housing prices, the bulk of the gains have gone to stock and bond speculators who’ve made out like bandits. As for consumers, well, they’re still stuck in the doldrums as economist Stephen S. Roach points out in this article at Project Syndicate. Here’s a clip:
“In the 22 quarters since early 2008, real personal-consumption expenditure… has grown at an average annual rate of just 1.1%, easily the weakest period of consumer demand in the post-World War II era.” (It’s also a) “massive slowdown from the pre-crisis pace of 3.6% annual real consumption growth from 1996 to 2007.” (“Occupy QE“, Stephen S. Roach, Project Syndicate)

So, personal consumption has dropped from 3.6% to 1.1%?!?

Yep. No wonder there’s no recovery. And, keep in mind, this is no short-term deal either, mainly because Democrats and Republicans are equally committed to future budget cuts which means it will be more difficult for households to get out of the red and resume spending. More austerity means more retrenchment and hard times for consumers, households and workers. Economist William R. Emmons provides a good summary of what’s-in-store for consumers in a recent post titled “Don’t Expect Consumer Spending To Be the Engine of Economic Growth It Once Was”. Here’s a clip from the article:
“Lower wealth: First and foremost, U.S. household wealth took a beating during the Great Recession. …., the loss of significant amounts of wealth and the severe pressure in some households to deleverage their balance sheets (reduce debt) are likely to contribute to restrained consumer spending for some time.

Stagnant incomes: The economic recovery under way since mid-2009 has been mediocre, at best. Job growth barely matches population growth, while incomes of the typical worker are barely keeping up with inflation. …, most of the overall gains in income appear to be flowing to high-income workers.

Tight credit: Consumer lenders either have disappeared altogether or are offering credit on a much more restricted basis than before the downturn.. …

Fragile confidence: Major consumer-confidence indexes have rebounded from their lowest levels during 2009 in the immediate aftermath of the recession, but they remain below the levels that prevailed just as the recession began in late 2008 …

Looming reversal of stimulus: The Federal Reserve has explored options to “exit” its extraordinarily accommodative monetary policy, while Congress and the president agree that budget consolidation is necessary in the not-too-distant future. In both cases, a tightening of policy measures represents a withdrawal of support for household incomes and wealth and, therefore, consumer spending.”

Individually, any of the five obstacles noted above might be surmountable. But combined, these contractionary forces make the outlook for broad-based consumer spending growth challenging. To be sure, some households weathered the economic and financial storms well, but we can’t count on these fortunate few to step up their spending sufficiently to offset the lost spending caused by declines in wealth, income, access to credit, confidence and government support.” (“Don’t Expect Consumer Spending To Be the Engine of Economic Growth It Once Was”, William R. Emmons, The Regional Economist |via The Big Picture

Emmons offers a bleak, but realistic assessment of our present predicament. There’s really no way the US economy can rebound without a dramatic reversal in the current fiscal policy. Most Americans appear to grasp this point which is why survey after survey show that the majority think the country is “on the wrong track”. The public’s frustration with Congress -(whose public approval rating is at all-time lows) is reflected in growing pessimism which is affecting their spending habits. This is completely normal, given that most middle income working people do not expect their financial situation to improve in the next year. Lower expectations mean more penny pinching, fewer job openings, skimpy net investment, and sluggish growth. That’s the future in a nutshell.

It’s worth noting that the investor class will also pay a heavy price for the current misguided policy. Stocks have had an impressive 4-year run, but there are signs that the day of reckoning is fast approaching. Get a load of this from USA Today:
“A potential warning to stock investors: the fourth-quarter earnings pre-announcement season is shaping up to be the most negative on record. In what seems like a major disconnect, the number of profit warnings relative to upbeat guidance is the widest it has ever been — at a time when the U.S. stock market is trading near record territory. The Standard & Poor’s 500 index notched a new closing high of 1809 Monday.

For every 10 companies warning of weaker-than-expected earnings for the October-through-December period, only one has said it will top forecasts, says earnings-tracker Thomson Reuters I/B/E/S. The actual 10.4-to-1 negative-to-positive pre-announcement ratio is on track to eclipse the prior record of 6.8 warnings for every positive one back in the first quarter of 2001. The long-term ratio is 2.3 warnings for each positive one.

“This is off the charts, I’ve never seen it this high,” says Gregory Harrison, analyst at Thomson Reuters.” (“As stocks hit record highs, so do profit warnings”, USA Today)

So why is Wall Street taking such dire warnings in their stride, you ask?

It’s because investors no longer pay attention to the fundamentals. Demand doesn’t matter. Earnings don’t matter. What matters is the Fed and the Fed alone. “Is Bernanke going to keep pumping trillions in liquidity into the financial markets or not?” That’s the policy upon which all investment decisions are made.

So when Bernanke announces his plan to “taper” his asset purchases (scale-back QE), equities will adjust accordingly.

Did somebody say “crash”?

Saturday, November 30, 2013

The Money Changers Serenade: A New Plot Hatches

Paul Craig Roberts

Former Treasury Secretary Timothy Geithner, a protege of Treasury Secretaries Rubin and Summers, has received his reward for continuing the Rubin-Summers-Paulson policy of supporting the “banks too big to fail” at the expense of the economy and American people. For his service to the handful of gigantic banks, whose existence attests to the fact that the Anti-Trust Act is a dead-letter law, Geithner has been appointed president and managing director of the private equity firm, Warburg Pincus and is on his way to his fortune.

A Warburg in-law financed Woodrow Wilson’s presidential campaign. Part of the reward was Wilson’s appointment of Paul Warburg to the first Federal Reserve Board. The symbiotic relationship between presidents and bankers has continued ever since. The same small clique continues to wield financial power.

Geithner’s career is illustrative. In the 1980s, Geithner worked for Kissinger Associates. In the mid to late 1990s, Geithner served as a deputy assistant Treasury secretary. Under Rubin and Summers he moved up to undersecretary of the Treasury.

From the Treasury he went to the Council on Foreign Relations and from there to the International Monetary Fund (IMF). From there he was appointed president of the Federal Reserve Bank of New York, where he worked to make banks more profitable by allowing higher ratios of debt to capital, thus contributing to the financial crisis.

Geithner arranged the sale of the failed Wall Street firm of Bear Stearns, helped with the taxpayer bailout of AIG, and rejected saving Lehman Brothers from bankruptcy in order to create the crisis atmosphere needed to more fully subordinate US economic policy to the needs of the few large banks.

Rubin, a 26-year veteran of Goldman Sachs, was rewarded by Citibank for his service to the banks while Treasury Secretary with a $50 million compensation package in 2008 and $126,000,000 between 1999 and 2009.

When a person becomes a Treasury official it is made clear that the choice is between serving the banks and becoming rich or trying to serve the public and becoming poor. Few make the latter choice.

As MIchael Hudson has informed us, the goal of the financial sector has always been to convert all income, from corporate profits to government tax revenues, to the service of debt. From the bankers standpoint, the more debt the richer the bankers. Rubin, Summers, Paulson, Geithner, and now banker Treasury Secretary Jack Lew faithfully serve this goal.

The Federal Reserve describes its policy of Quantitative Easing — the creation of new money with which the Fed purchases Treasury debt and mortgage backed securities — as a low interest rate policy in order to stimulate employment and economic growth. Economists and the financial media have parroted this cover story.

In contrast, I have exposed QE as a scheme for pumping profits into the banks and boosting their balance sheets. The real purpose of QE is to drive up the prices of the debt-related derivatives on the banks’ books, thus keeping the banks with solvent balance sheets.

Writing in the Wall Street Journal (“Confessions of a Quantitative Easer,” November 11, 2013), Andrew Huszar confirms my explanation to be the correct one. Huszar is the Federal Reserve official who implemented the policy of QE. He resigned when he realized that the real purposes of QE was to drive up the prices of the banks’ holdings of debt instruments, to provide the banks with trillions of dollars at zero cost with which to lend and speculate, and to provide the banks with “fat commissions from brokering most of the Fed’s QE transactions.” (See: www.paulcraigroberts.org )

This vast con game remains unrecognized by Congress and the public. At the IMF Research Conference on November 8, 2013, former Treasury Secretary Larry Summers presented a plan to expand the con game.

Summers says that it is not enough merely to give the banks interest free money. More should be done for the banks. Instead of being paid interest on their bank deposits, people should be penalized for keeping their money in banks instead of spending it.

To sell this new rip-off scheme, Summers has conjured up an explanation based on the crude and discredited Keynesianism of the 1940s that explained the Great Depression as a problem caused by too much savings. Instead of spending their money, people hoarded it, thus causing aggregate demand and employment to fall.

Summers says that today the problem of too much saving has reappeared. The centerpiece of his argument is “the natural interest rate,” defined as the interest rate at which full employment is established by the equality of saving with investment. If people save more than investors invest, the saved money will not find its way back into the economy, and output and employment will fall.

Summers notes that despite a zero real rate of interest, there is still substantial unemployment. In other words, not even a zero rate of interest can reduce saving to the level of investment, thus frustrating a full employment recovery. Summers concludes that the natural rate of interest has become negative and is stuck below zero.

How to fix this? The way to fix it, Summers says, is to charge people for saving money. To avoid the charges, people would spend the money, thus reducing savings to the level of investment and restoring full employment.

Summers acknowledges that the problem with his solution is that people would take their money out of banks and hoard it in cash holdings. In other words, the cash form of money provides consumers with a freedom to save that holds down consumption and prevents full employment.

Summers has a fix for this: eliminate the freedom by imposing a cashless society where the only money is electronic. As electronic money cannot be hoarded except in bank deposits, penalties can be imposed that force unproductive savings into consumption.

Summers’ scheme, of course, is a harebrained one. With governments running huge deficits, who would purchase bonds at negative interest rates? How would pension and retirement funds operate? Would they also be subject to an annual percentage confiscation?

We know that the response of consumers to the long term decline in real median family income, to the loss of jobs from labor arbitrage across national borders (jobs offshoring), to rising homelessness, to cuts in the social safety net, to the transformation of their full time jobs to part time jobs (employers’ response to Obamacare), has been to reduce their savings rate. Indeed, few have any savings at all. The US personal saving rate is currently 2 percentage points, about 30%, below the long term average. Retired people, unable to earn any interest on their savings from the Fed’s zero interest rate policy, are being forced to draw down their savings in order to pay their bills.

Moreover, it is unclear whether the savings rate is an accurate measure or merely a residual of other calculations. With so many people having to draw down their savings, I wouldn’t be surprised if an accurate measure showed the personal savings rate to be negative.

But for Summers the plight of the consumer is not the problem. The problem is the profits of the banks. Summers has the solution, and the establishment, including Paul Krugman, is applauding it. Once the economy officially turns down again, watch out.

Monday, September 30, 2013

American Workers: Hanging on by the Skin of Their Teeth

by MIKE WHITNEY

After five years of Obama’s economic recovery, the American people are as gloomy as ever. According to a Bloomberg National Poll that was released this week, fewer people “are optimistic about the job market” or “the housing market” or “anticipate improvement in the economy’s strength over the next year.” Also, only 38 percent think that President Obama is doing enough “to make people feel more economically secure.” Worst of all, Bloomberg pollsters found that 68 percent of interviewees thought the country was “headed in the wrong direction”.

So why is everyone so miserable? Are things really that bad or have we turned into a nation of crybabies?

The reason people are so pessimistic is because the economy is still in the doldrums and no one’s doing anything about it. That’s it in a nutshell. Survey after survey have shown that what people really care about is jobs, but no one in Washington is listening. In fact, jobs aren’t even on Obama’s radar. Just look at his record. He’s worse than any president in modern times. Take a look at this graph.

More than 600,000 good-paying public sector jobs have been slashed during Obama’s tenure as president. That’s worse than Bush, worse than Clinton, worse than Reagan, worse than anyone, except maybe Hoover. Is that Obama’s goal, to one-up Herbert Hoover?

Obama has done everything he could to make the lives of working people as wretched as possible. Do you remember the Card Check sellout or the Wisconsin “flyover” when Governor Scott Walker was eviscerating collective bargaining rights for public sector unions and Obama blew kisses from Airforce One on his way to a campaign speech in Minnesota? Nice touch, Barry. Or what about the “Job’s Czar” fiasco, when Obama appointed GE’s outsourcing mandarin Jeffrey Immelt to the new position just in time for GE to lay off another 950 workers at their locomotive plant in Pennsylvania. That’s tells you what Obama really thinks about labor.

What Obama cares about is trimming the deficits and keeping Wall Street happy. That’s it. But the people who elected him don’t want him to cut the deficits, because cutting the deficits prolongs the slump and costs jobs. What they want is more stimulus, so people can find work, feed their families, and have some basic security. That’s what they want, but they’re not going to get it from Obama because he doesn’t work for them. He works for the stuffed shirts who flank him on the golf course at Martha’s Vineyard or the big shots who chow down with him at his $100,000-per-plate campaign jamborees. That’s his real constituency. Everyone else can take a flying fu** for all he cares.

Then there’s the Fed. Most people don’t think the Fed’s goofy programs work at all. They think it’s all a big ruse. They think Bernanke is just printing money and giving it to his criminal friends on Wall Street (which he is, of course.) Have you seen this in the New York Times:
“Only one in three Americans has confidence in the Federal Reserve’s ability to promote economic growth, while little more than a third think the Fed is spinning its wheels, according to a New York Times/CBS News poll….

The Fed has been trying for five years to speed the nation’s recovery from the Great Recession by reducing borrowing costs to the lowest levels on record….

Most Americans, it would appear, remain either unaware or unpersuaded.” (“Majority of Americans Doubt Benefits of Fed Stimulus“, New York Times)

“Unpersuaded”? Are you kidding me? Most Americans think they’re getting fleeced; unpersuaded has nothing to do with it. They’re not taken in by the QE-mumbo jumbo. They may not grasp the finer-points, but they get the gist of it, which is that the Fed has run up a big $3 trillion bill every penny of which has gone to chiseling shysters on Wall Street. They get that! Everyone gets that! Sure, if you want to get into the weeds about POMO or the byzantine aspects of the asset-purchase program, you might detect a bit of confusion, but –I assure you–the average Joe knows what’s going on. He knows all this quantitative jabberwocky is pure bunkum and that he’s getting schtooped bigtime. You don’t need a sheepskin from Princeton to know when you’ve been had.

And that’s why everyone is so pessimistic, because they know that the Fed, the administration and the media are all lying to them 24-7. That’s why–as Bloomberg discovered–”Americans are losing faith in the nation’s economic recovery.” Because they don’t see any recovery. As far as they’re concerned, the economy is still in recession. After all, they’re still underwater on their mortgages, Grandpa Jack just took a job at a fast-food joint to pay for his wife’s heart medication, and junior is camped out in the basement until he can get a handle on his $45,000 heap of college loans. So where’s the recovery?

Nobody needs Bloomberg to point out how grim things are for the ordinary people. They see it firsthand every damn day.
Did you catch the news on Wal-Mart this week? It’s another story that helps explain why everyone’s so down-in-the-mouth. Here’s what happened: Wal-Mart’s stock tanked shortly after they announced that their “inventory growth …had outstripped sales gains in the second quarter…. Merchandise has been piling up because consumers have been spending less freely than Wal-Mart projected….” (Bloomberg)

Okay, so the video games and Barbie dolls are piling up to the rafters because part-time wage slaves who typically shop at Wal-Mart are too broke to buy anything but the basic necessities. Is that what we’re hearing?

Indeed. “We are managing our inventory appropriately,” David Tovar, a Wal-Mart spokesman, said today in a telephone interview. “We feel good about our inventory position.”

Sure, you do, Dave. Here’s more from Bloomberg:
“US. chains are already bracing for a tough holiday season, when sales are projected to rise 2.4 percent, the smallest gain since 2009, according to ShopperTrak, a Chicago-based firm. Wal-Mart cut its annual profit forecast after same-store sales fell 0.3 percent in the second quarter. …

Wal-Mart’s order pullback is affecting suppliers in various categories, including general merchandise and apparel, said the supplier, who has worked with Wal-Mart for almost two decades and asked not to be named to protect his relationship with the company. He said he couldn’t recall the retailer ever planning ordering reductions two quarters in advance.” (“Wal-Mart Cutting Orders as Unsold Merchandise Piles Up”, Bloomberg)

So we’re back to 2009?

Looks like it. When the nation’s biggest retailer starts trimming its sails, it ripples through the whole industry. It means softer demand, shorter hours, and more layoffs. Get ready for a lean Christmas.

The Walmart story just shows that people are at the end of their rope. For the most part, these are the working poor, the people the Democratic Party threw overboard a couple decades ago when they decided to hop in bed with Wall Street. Now their hardscrabble existence is becoming unbearable; they can’t even scrape together enough cash to shop the discount stores. That means we’re about one step from becoming a nation of dumpster divers. Don’t believe it? Then check out this clip from CNN Money:
“Roughly three-quarters of Americans are living paycheck-to-paycheck, with little to no emergency savings, according to a survey released by Bankrate.com Monday. Fewer than one in four Americans have enough money in their savings account to cover at least six months of expenses, enough to help cushion the blow of a job loss, medical emergency or some other unexpected event, according to the survey of 1,000 adults. Meanwhile, 50% of those surveyed have less than a three-month cushion and 27% had no savings at all..

Last week, online lender CashNetUSA said 22% of the 1,000 people it recently surveyed had less than $100 in savings to cover an emergency, while 46% had less than $800. After paying debts and taking care of housing, car and child care-related expenses, the respondents said there just isn’t enough money left over for saving more.” (“76% of Americans are living paycheck-to-paycheck“, CNN Money)

Savings? What’s that? Do you really think people can save money on $30,000 or $40,000 a year feeding a family of four?

Dream on. Even an unexpected trip to the vet with pet Fido is enough to push the family budget into the red for months to come. Savings? Don’t make me laugh.

The truth is, most people are hanging on by the skin of their teeth. They can’t make ends meet on their crappy wages and they’re too broke to quit. There’s no way out. It’s obvious in all the data. And it’s hurting the economy, too, because spending drives growth, but you can’t spend when you’re busted. Economist Stephen Roach made a good point in a recent article at Project Syndicate. He said,
“In the 22 quarters since early 2008, real personal-consumption expenditure, which accounts for about 70% of US GDP, has grown at an average annual rate of just 1.1%, easily the weakest period of consumer demand in the post-World War II era.” (It’s also a) “massive slowdown from the pre-crisis pace of 3.6% annual real consumption growth from 1996 to 2007.” (“Occupy QE“, Stephen S. Roach, Project Syndicate)

So the economy is getting hammered because consumption is down. And working people are getting hammered because jobs are scarce and wages are flat. But we live in the richest country in the world, right?

Right. So what’s wrong with this picture?

Sunday, April 28, 2013

Recovery for the 7 Percent

April 28, 2013 — Paul Craig Roberts

“From the end of the recession in 2009 through 2011 (the last year for which Census Bureau wealth data are available), the 8 million households in the U.S. with a net worth above $836,033 saw their aggregate wealth rise by an estimated $5.6 trillion, while the 111 million households with a net worth at or below that level saw their aggregate wealth decline by an estimated $600 billion.” ~ Pew Research, An Uneven Recovery, by Richard Fry and Paul Taylor.

Since the recession was officially declared to be over in June 2009, I have assured readers that there has been no recovery. Gerald Celente, John Williams (shadowstats.com), and no doubt others have also made it clear that the alleged recovery is an artifact of an understated inflation rate that produces an image of real economic growth.

Now comes the Pew Research Center with its conclusion that the recession ended only for the top 7 percent of households that have substantial holdings of stocks and bonds. The other 93% of the American population is still in recession.

The Pew report attributes the recovery for the affluent to the rise in the stock and bond markets, but does not say what caused these markets to rise.

The stock market’s recovery does not reflect rising consumer purchasing power and retail sales. The labor force is shrinking, not growing. Job growth lags population growth, and the few jobs that are created are primarily dead-end jobs in lowly paid domestic services. Retail sales adjusted for inflation and real median household income have been bottom bouncing since 2009.

To the extent that there is profit growth in US corporations, it comes from labor cost savings from offshoring US jobs and from bringing in foreign workers on work visas. By lowering labor costs, corporations boost profits and thereby capital gains for those 7 percent who have large holdings of financial assets. Those in the 93 percent who are displaced by foreign workers experience income reductions. This transfer of the incomes of the 93 percent to the 7 percent via jobs offshoring and work visas is the reason for the stark rise in US income inequality.
Another source of the stock market’s rise is the Federal Reserve’s policy of quantitative easing, that is, the printing of $1,000 billion dollars annually with which to support the too-big-to-fail banks’ balance sheets and to finance the federal budget deficit. The cash that the Fed is pouring into the banks is not finding its way into business and consumer loans, but the money is available for the banks to speculate in derivatives and stock market futures. Thus, the Fed’s policy, which is directed at keeping afloat a few oversized banks, also benefits the 7 percent by driving up the value of their stock portfolios.

The reason bond prices are so high that real interest rates are negative is that the Fed is purchasing $1,000 billion of mortgage-backed “securities” and US Treasury debt annually. The lower the Fed forces interest rates, the higher go bond prices. If you are among the 7 percent, the Fed has produced capital gains for your bond portfolio. But if you are a saver among the 93 percent, you are losing purchasing power because the interest you receive is less than the rate of inflation.

The Pew report puts it this way: Since the “recovery” that began in June 2009, wealthy households experienced a 28 percent rise in their net worth, while everyone else lost 4 percent of their assets.

Is this the profile of a democracy in which government serves the public interest, or is it the profile of a financial aristocracy that uses government to grind the population under foot?

Wednesday, February 6, 2013

Want to Fix the Economy? Spend More Money

Can't Get No Stimulation
by MIKE WHITNEY


The economy operates on a simple principle: When people spend money, the economy grows. That means the goal of economic policy should be to maintain a level of spending that keeps the economy growing and minimizes the unavoidable peaks and valleys of the business cycle. This can’t be done without government intervention, mainly because free market capitalism tends to be too erratic (spending can fall sharply) and crisis prone. (See: Lehman Brothers 2008). Dramatic fluctuations in the markets, typically result in anemic business investment which leads to higher unemployment, slower growth and weaker demand. This problem was largely solved by British economist John Maynard Keynes. Keynes understood that when private sector spending dropped off, public sector (government) spending had to increase or output would shrink, unemployment would rise, and the economy would begin to sputter.

Interestingly, all of the main players who are currently setting policy in the Obama administration and at the Federal Reserve have some understanding of Keynes’ theories and how they can be used to put the economy back on track. The fact that Keynes remedies have been rejected in favor of unconventional and ineffective theories like QE (Quantitative Easing), suggests that the supporters of these policies are less interested in reviving the economy and putting people back to work, then they are with rewarding powerful constituents. 5 years of experimentation, has resulted in chronic high unemployment, droopy consumer confidence, negative wage growth, sky-high foreclosures and personal bankruptcies, record food stamp usage, and a sharp increase in extreme poverty. At the same time, the 3 main stock indicies have more than doubled in value while financial institutions and corporations are raking in record profits. There’s no doubt that QE has served the interests of the few while hurting the interests of the many.

The reason Keynes theories experienced a “comeback” in 2009 is not hard to grasp. Congress and the White House were afraid that the financial system was about to collapse. That’s why Obama’s team of economics advisors–led by Lawrence Summers–pushed through the $800 billion American Recovery and Reinvestment Act (ARRA), because, when the chips were down, economists turned to the tried-and-true remedies of John Maynard Keynes. And they worked, too, the only drawback was that the amount of the stimulus was too small to produce the recovery that had been promised. (For the latest on the effectiveness of the stimulus, see: “Joe Scarborough’s Attack on Stimulus“, Dean Baker, CEPR)

Critics of Obama’s fiscal stimulus say that “It didn’t work”, but the claim is ridiculous. How could it not work? Stimulus is not some magic elixir that works on one subject and not on another. It’s spending. Spending is activity, spending is growth, spending is demand, spending is hiring, spending is stimulus. Spending is everything. When the government spends money, it has the same effect as when a consumer spends money or a business spends money. Therefore, the stimulus worked.

The economy is not a sentient being. The economy doesn’t care if private citizens do the spending or the government does the spending. It doesn’t care if the money comes from personal bank accounts or budget deficits. The economy doesn’t care if the money is spent on cancer research or pet rocks. It doesn’t matter, because all spending increases activity, strengthens demand, and leads to more hiring. Saving has the opposite effect. While saving may be the necessary and sensible choice for an individual, it’s poison for the economy. When people save, the velocity of money decreases, demand weakens and growth slows. This whole question of saving vs spending is basic to Keynes’ view of how the economy works. Here’s an example which helps to explain:
“Let’s imagine there are only two people in the world, you and your friend…..You make $100 a week by selling milk to your friend at $1 a bottle, and he makes $100 a week because you buy chocolate from him at $1 a bar. The entire income in this economy (its Gross Domestic Product or GDP) is $200, which corresponds to 100 bottles of milk and 100 bars of chocolate.

One day you make a decision to save $20 out of your $100 and hold it in cash. Consequently, my income falls to $80, and the sum income in the economy is now $180, and the economy produces 20 chocolate bars less than before. In the subsequent week, I only have $80 to spend, hence your takings also fall to $80, and you buy a smaller amount of my milk.

In the end, you and your friend’s incomes are smaller and you are producing and consuming less than is potentially possible. Your economy has fallen into recession.

So now we have a recession but how do we get out of it? Well the neoclassical free market thinking is that you simply do nothing and the forex market will correct itself. In our example you will reduce the price of milk until you are selling 100 bottles again. Your friend does the same and he is now selling 100 bars of chocolate again. The recession is over.

However, this doesn’t happen overnight and could take a while, months even years. So Keynes advocates intervention by the state. Say the state printed $20 and bought your unsold produce, then you would be back to a monthly income of $100 and so would your friend because your income is his income. Full production is immediate therefore no recession and no reduction in GDP.” (“The Basics of Keynesian Economics”, etoro.com)

While imperfect, this analogy helps us get a better fix on what’s going on in the economy today. Presently, output is below what it should be by more than $1 trillion per year, thus, unemployment is high and growth is weak. At the same time, personal savings have risen from near-zero in 2007 to almost 4 percent today. The increase in savings has decreased spending which, in turn, has reduced activity and demand. According to Keynes, the state should step in and boost its spending to employ more of the economy’s resources and put more people back to work. Then, as the recovery gains momentum, the state can reduce its contribution and trim the deficits.

The GOP deficit hawks in Congress want to do the exact opposite. They want to want to reduce the deficits by cutting public spending on popular social programs like Medicare and Social Security. This is a mistake that will only deepen the crisis and pave the way for another slump. It is fairly easy to see what’s wrong with this view by looking at last week’s Commerce Department report on GDP. On Thursday, the Commerce Department reported that 4th Quarter growth (2012) had slipped into negative territory due to a sharp reduction in business inventories and defense spending. This sent off alarms across the country. Was the report a “one off” or is the economy really headed back into recession? That’s what everyone wants to know. (A recession is defined as two consecutive quarters of negative growth)

Now many people think that less money going to fatcat defense contractors is a good thing, and I agree. But as we said earlier, the economy doesn’t make value judgements like that. Spending is spending, and when government spending falls (as it did), the economy edges closer to recession. Now apply this same rule to the recommendations of the GOP deficit hawks. The hawks say they want “fiscal responsibility”, but what they’re opting for is another slump because the trillion dollar deficits (which represent $1 trillion of additional government spending) are the only thing keeping the economy from sliding back into recession. (See the breakdown of GDP report here).

So how do we reduce the deficits without pushing the economy back into recession?

Increase personal consumption? That seems like the logical choice, after all, if consumers go on another spending spree, then businesses will hire more workers, the economy will grow, federal revenues will balloon, and the deficits will vanish automatically. Problem solved, right?

The only thing is that–according to the data—personal consumption is just about back to normal now. That suggests that the problem isn’t consumption, the problem is that people are not spending as much as they did during the bubble years when residential construction was at its peak and homeowners were feeling flush due to rising housing prices. That hyper-spending was a result of fictitious equity, lax lending standards, low interest rates and massive fraud. The goal of policy should not be to create those same conditions again, (and increase the probability of another meltdown!) but to look for solutions elsewhere.

So, where do we look if not to more personal consumption? Business investment?

It’s unreasonable to expect businesses to make more products when demand is weak. They’d rather issue bigger dividends or buyback more of their own stock (which they have been doing) instead of building more widgets that will just sit on warehouse shelves.

So if neither consumers nor businesses can fill the gap (and reduce the deficits), then what about the government? In the short-term, that’s the best choice, especially since money is so cheap. Presently, the gov can borrow money at historic low rates–(10-year US Treasuries are currently below 2%). The administration should take advantage of these low rates and deploy more stimulus to kickstart the economy. As the economy gets back to full-steam, the deficits will shrink on their own and policymakers can work on a plan for long-term debt reduction.

So what should Obama be doing?

The Obama administration should launch an aggressive government-funded jobs program aimed at lowering unemployment by rebuilding the nation’s dilapidated infrastructure. The commitment of trillions of dollars in fiscal stimulus to the stated project would push the dollar lower which would reduce the trade deficit (US exports would become more competitive) while increasing domestic national savings. Full employment would put more money in the hands of people who would spent it quickly which would increase activity, demand and growth.

So the way to fix the economy is to use government resources to put people back to work. As Keynes opined in his masterpiece “The General Theory of Employment, Interest and Money”: “I am now somewhat sceptical of the success of a merely monetary policy directed towards influencing the rate of interest. I expect to see the State… taking an ever greater responsibility for directly organising investment; since it seems likely that the fluctuations in the market estimation of the marginal efficiency of different types of capital…. will be too great to be offset by any practicable changes in the rate of interest.”

In other words, interest rates and monetary policy alone, won’t get the job done. (Isn’t that obvious after 5 years of zero interest rate policy, ZIRP, and QE??) The government has to take the lead in directing investment to produce a strong and sustainable recovery. That’s what Obama should be doing.

Tuesday, January 8, 2013

America's Deceptive Fiscal Cliff

How Today’s Fiscal Austerity is Reminiscent of World War I’s Economic Misunderstandings
by MICHAEL HUDSON

When World War I broke out in August 1914, economists on both sides forecast that hostilities could not last more than about six months. Wars had grown so expensive that governments quickly would run out of money. It seemed that if Germany could not defeat France by springtime, the Allied and Central Powers would run out of savings and reach what today is called a fiscal cliff and be forced to negotiate a peace agreement.

But the Great War dragged on for four destructive years. European governments did what the United States had done after the Civil War broke out in 1861 when the Treasury printed greenbacks. They paid for more fighting simply by printing their own money. Their economies did not buckle and there was no major inflation. That would happen only after the war ended, as a result of Germany trying to pay reparations in foreign currency. This is what caused its exchange rate to plunge, raising import prices and hence domestic prices. The culprit was not government spending on the war itself (much less on social programs).

But history is written by the victors, and the past generation has seen the banks and financial sector emerge victorious. Holding the bottom 99% in debt, the top 1% are now in the process of subsidizing a deceptive economic theory to persuade voters to pursue policies that benefit the financial sector at the expense of labor, industry, and democratic government as we know it.

Wall Street lobbyists blame unemployment and the loss of industrial competitiveness on government spending and budget deficits – especially on social programs – and labor’s demand to share in the economy’s rising productivity. The myth (perhaps we should call it junk economics) is that (1) governments should not run deficits (at least, not by printing their own money), because (2) public money creation and high taxes (at lest on the wealthy) cause prices to rise. The cure for economic malaise (which they themselves have caused), is said to be less public spending, along with more tax cuts for the wealthy, who euphemize themselves as “job creators.” Demanding budget surpluses, bank lobbyists promise that banks can provide the economy with enough purchasing power to grow. Then, when this ends in crisis, they insist that austerity can squeeze out enough income to enable private-sector debts to be paid.

The reality is that when banks load the economy down with debt, this leaves less to spend on domestic goods and services while driving up housing prices (and hence the cost of living) with reckless credit creation on looser lending terms. Yet on top of this debt deflation, bank lobbyists urge fiscal deflation: budget surpluses rather than pump-priming deficits. The effect is to further reduce private-sector market demand, shrinking markets and employment. Governments fall deeper into distress, and are told to sell off land and natural resources, public enterprises, and other assets. This creates a lucrative market for bank loans to finance privatization on credit. This explains why financial lobbyists back the new buyers’ right to raise the prices they charge for basic needs, creating a united front to endorse rent extraction. The effect is to enrich the financial sector owned by the 1% in ways that indebt and privatize the economy at large – individuals, business and the government itself.

This policy was exposed as destructive in the late 1920s and early 1930s when John Maynard Keynes, Harold Moulton and a few others countered the claims of Jacques Rueff and Bertil Ohlin that debts of any magnitude could be paid if governments would impose deep enough austerity and suffering. This is the doctrine adopted by the International Monetary

Fund to impose on Third World debtors since the 1960s, and by European neoliberals defending creditors imposing austerity on Ireland, Greece, Spain and Portugal.

This pro-austerity mythology aims to distract the public from asking why peacetime governments can’t simply print the money they need. Given the option of printing money instead of levying taxes, why do politicians only create new spending power for the purpose of waging war and destroying property, not to build or repair bridges, roads and other public infrastructure? Why should the government tax employees for future retirement payouts, but not Wall Street for similar user fees and financial insurance to build up a fund to pay for future bank over-lending crises? For that matter, why doesn’t the U.S. Government print the money to pay for Social Security and medical care, just as it created new debt for the $13 trillion post-2008 bank bailout? (I will return to this question below.)

The answer to these questions has little to do with markets, or with monetary and tax theory. Bankers claim that if they have to pay more user fees to pre-fund future bad-loan claims and deposit insurance to save the Treasury or taxpayers from being stuck with the bill, they will have to charge customers more – despite their current record profits, which seem to grab everything they can get. But they support a double standard when it comes to taxing labor.

Shifting the tax burden onto labor and industry is achieved most easily by cutting back public spending on the 99%. That is the root of the December 2012 showdown over whether to impose the anti-deficit policies proposed by the Bowles-Simpson commission of budget cutters whom President Obama appointed in 2010. Shedding crocodile tears over the government’s failure to balance the budget, banks insist that today’s 15.3% FICA wage withholding be raised – as if this will not raise the break-even cost of living and drain the consumer economy of purchasing power. Employers and their work force are told to save in advance for Social Security or other public programs. This is a disguised income tax on the bottom 99%, whose proceeds are used to reduce the budget deficit so that taxes can be cut on finance and the 1%. To paraphrase Leona Helmsley’s quip that “Only the little people pay taxes,” the post-2008 motto is that only the 99% have to suffer losses, not the 1% as debt deflation plunges real estate and stock market prices to inaugurate a Negative Equity economy while unemployment rates soar.

There is no more need to save in advance for Social Security than there is to save in advance to pay for war. Selling Treasury bonds to pay for retirees has the identical monetary and fiscal effect of selling newly printed securities. It is a charade – to shift the tax burden onto labor and industry. Governments need to provide the economy with money and credit to expand markets and employment. They do this by running budget deficits, and this can be done by creating their own money. That is what banks oppose, accusing it of leading to hyperinflation rather than help economies grow.

Their motivation for this wrong accusation is self-serving and their logic is deceptive. Bankers always have fought to block government from creating its own money – at least under normal peacetime conditions. For many centuries, government bonds were the largest and most secure investment for the financial elites that hold most savings. Investment bankers and brokers monopolized public finance, at substantial underwriting commissions. The market for stocks and corporate bonds was rife with fraud, dominated by insiders for the railroads and great trusts being organized by Wall Street, and the canal ventures organized by French and British stockbrokers.

However, there was little alternative to governments creating their own money when the costs of waging an international war far exceeded the volume of national savings or tax revenue available. This obvious need quieted the usual opposition mounted by bankers to limit the public monetary option. It shows that governments can do more under force majeur emergencies than under normal conditions. And the September 2008 financial crisis provided an opportunity for the U.S. and European governments to create new debt for bank bailouts. This turned out to be as expensive as waging a war. It was indeed a financial war. Banks already had captured the regulatory agencies to engage in reckless lending and a wave of fraud and corruption not seen since the 1920s. And now they were holding economies hostage to a break in the chain of payments if they were not bailed out for their speculative gambles, junk mortgages and fraudulent loan packaging.

Their first victory was to disable the ability – or at least the willingness – of the Treasury, Federal Reserve and Comptroller of the Currency to regulate the financial sector. Goldman Sachs, Citicorp and their fellow Wall Street giants hold veto power the appointment of key administrators at these agencies. They used this beachhead to weed out nominees who might not favor their interests, preferring ideological deregulators in the stripe of Alan Greenspan and Tim Geithner. As John Kenneth Galbraith quipped, a precondition for obtaining a central bank post is tunnel vision when it comes to understanding that governments can create their credit as readily as banks can. What is necessary is for one’s political loyalties to lie with the banks.

In the post-2008 financial wreckage it took only a series of computer keystrokes for the U.S. Government to create $13 trillion in debt to save banks from suffering losses on their reckless real estate loans (which computer models pretended would make banks so rich that they could pay their managers enormous salaries, bonuses and stock options), insurance bets gone bad (underpricing risk to win business to pay their managers enormous salaries and bonuses), arbitrage gambles and outright fraud (to give the illusion of earnings justifying enormous salaries, bonuses and stock options). The $800 billion Troubled Asset Relief Program (TARP) and $2 trillion of Federal Reserve “cash for trash” swaps enabled the banks to continue their remuneration of executives and bondholders with hardly a hiccup – while incomes and wealth plunged for the remaining 99% of Americans.

A new term, Casino Capitalism, was coined to describe the transformation that finance capitalism was undergoing in the post-1980 era of deregulation that opened the gates for banks to do what governments hitherto did in time of war: create money and new public debt simply by “printing it” – in this case, electronically on their computer keyboards.

Taking the insolvent Fannie Mae and Freddie Mac mortgage financing agencies onto the public balance sheet for $5.2 trillion accounted for over a third of the $13 trillion bailout. This saved their bondholders from having to suffer losses from the fraudulent appraisals on the junk mortgages with which Countrywide, Bank of America, Citibank and other “too big to fail” banks had stuck them. This enormous debt increase was done without raising taxes. In fact, the Bush administration cut taxes, giving the largest cuts to the highest income and wealth brackets who were its major campaign contributors. Special tax privileges were given to banks so that they could “earn their way out of debt” (and indeed, out of negative equity).[1] The Federal Reserve gave a free line of credit (Quantitative Easing) to the banking system at only 0.25% annual interest by 2011 – that is, one quarter of a percentage point, with no questions asked about the quality of the junk mortgages and other securities pledged as collateral at their full face value, which was far above market price.

This $13 trillion debt creation to save banks from having to suffer a loss was not accused of threatening economic stability. It enabled them to resume paying exorbitant salaries and bonuses, dividends to bondholders and also to pay counterparties on casino-capitalist arbitrage bets. These payments have helped the 1% receive a reported 93% of the gains in income since 2008. The bailout thus polarized the economy, giving the financial sector more power over labor and consumers, industry and the government than has been the case since the late 19th-century Gilded Age.

All this makes today’s financial war much like the aftermath of World War I and countless earlier wars. The effect is to impoverish the losers, appropriate hitherto public assets for the victors, and impose debt service and taxes much like levying tribute. “The financial crisis has been as economically devastating as a world war and may still be a burden on ‘our grandchildren,’” Bank of England official Andrew Haldane recently observed. “‘In terms of the loss of incomes and outputs, this is as bad as a world war.’ he said. The rise in government debt has prompted calls for austerity – on the part of those who did not receive the giveaway. ‘It would be astonishing if people weren’t asking big questions about where finance has gone wrong.’”[2]

But as long as the financial sector is winning its war against the economy at large, it prefers that people believe that There Is No Alternative. Having captured mainstream economics as well as government policy, finance seeks to deter students, voters and the media from questioning whether the financial system really needs to be organized in the way it is. Once such a line of questioning is pursued, people may realize that banking, pension and Social Security systems and public deficit financing do not have to be organized in the way they are. There are better alternatives to today’s road to austerity and debt peonage.


The Financial War Against the Economy at Large

Today’s economic warfare is not the kind waged a century ago between labor and its industrial employers. Finance has moved to capture the economy at large, industry and mining, public infrastructure (via privatization) and now even the educational system. (At over $1 trillion, U.S. student loan debt came to exceed credit-card debt in 2012.) The weapon in this financial warfare is no longer military force. The tactic is to load economies (governments, companies and families) with debt, siphon off their income as debt service and then foreclose when debtors lack the means to pay. Indebting government gives creditors a lever to pry away land, public infrastructure and other property in the public domain. Indebting companies enables creditors to seize employee pension savings. And Indebting labor means that it no longer is necessary to hire strikebreakers to attack union organizers and strikers.

Workers have become so deeply indebted on their home mortgages, credit cards and other bank debt that they fear to strike or even to complain about working conditions. Losing work means missing payments on their monthly bills, enabling banks to jack up interest rates to levels that used to be deemed usurious. So debt peonage and unemployment loom on top of the wage slavery that was the main focus of class warfare a century ago. And to cap matters, credit-card bank lobbyists have rewritten the bankruptcy laws to curtail debtor rights, and the referees appointed to adjudicate disputes brought by debtors and consumers are subject to veto from the banks and businesses that are mainly responsible for inflicting injury.

The aim of financial warfare is not merely to acquire land, natural resources and key infrastructure rents as in military warfare; it is to centralize creditor control over society. In contrast to the promise of democratic reform nurturing a middle class a century ago, we are witnessing a regression to a world of special privilege in which one must inherit wealth in order to avoid debt and job dependency.

The emerging financial oligarchy seeks to shift taxes off banks and their major customers (real estate, natural resources and monopolies) onto labor. Given the need to win voter acquiescence, this aim is best achieved by rolling back everyone’s taxes. The easiest way to do this is to shrink government spending, headed by Social Security, Medicare and Medicaid. Yet these are the programs that enjoy the strongest voter support. This fact has inspired what may be called the Big Lie of our epoch: the pretense that governments can only create money to pay the financial sector, and that the beneficiaries of social programs should be entirely responsible for paying for Social Security, Medicare and Medicaid, not the wealthy. This Big Lie is used to reverse the concept of progressive taxation, turning the tax system into a ploy of the financial sector to levy tribute on the economy at large.

Financial lobbyists quickly discovered that the easiest ploy to shift the cost of social programs onto labor is to conceal new taxes as user fees, using the proceeds to cut taxes for the elite 1%. This fiscal sleight-of-hand was the aim of the 1983 Greenspan Commission. It confused people into thinking that government budgets are like family budgets, concealing the fact that governments can finance their spending by creating their own money. They do not have to borrow, or even to tax (at least, not tax mainly the 99%).

The Greenspan tax shift played on the fact that most people see the need to save for their own retirement. The carefully crafted and well-subsidized deception at work is that Social Security requires a similar pre-funding – by raising wage withholding. The trick is to convince wage earners it is fair to tax them more to pay for government social spending, yet not also to ask the banking sector to pay similar a user fee to pre-save for the next time it itself will need bailouts to cover its losses. Also asymmetrical is the fact that nobody suggests that the government set up a fund to pay for future wars, so that future adventures such as Iraq or Afghanistan will not “run a deficit” to burden the budget. So the first deception is to treat only Social Security and medical care as user fees. The second is to aggravate matters by insisting that such fees be paid long in advance, by pre-saving.

There is no inherent need to single out any particular area of public spending as causing a budget deficit if it is not pre-funded. It is a travesty of progressive tax policy to only oblige workers whose wages are less than (at present) $105,000 to pay this FICA wage withholding, exempting higher earnings, capital gains, rental income and profits. The raison d’être for taxing the 99% for Social Security and Medicare is simply to avoid taxing wealth, by falling on low wage income at a much higher rate than that of the wealthy. This is not how the original U.S. income tax was created at its inception in 1913. During its early years only the wealthiest 1% of the population had to file a return. There were few loopholes, and capital gains were taxed at the same rate as earned income.

The government’s seashore insurance program, for instance, recently incurred a $1 trillion liability to rebuild the private beaches and homes that Hurricane Sandy washed out. Why should this insurance subsidy at below-commercial rates for the wealthy minority who live in this scenic high-risk property be treated as normal spending, but not Social Security? Why save in advance by a special wage tax to pay for these programs that benefit the general population, but not levy a similar “user fee” tax to pay for flood insurance for beachfront homes or war? And while we are at it, why not save another $13 trillion in advance to pay for the next bailout of Wall Street when debt deflation causes another crisis to drain the budget?

But on whom should we levy these taxes? To impose user fees for the beachfront reconstruction would require a tax falling mainly on the wealthy owners of such properties. Their dominant role in funding the election campaigns of the Congressmen and Senators who draw up the tax code suggests why they are able to avoid prepaying for the cost of rebuilding their seashore property. Such taxation is only for wage earners on their retirement income, not the 1% on their own vacation and retirement homes.

By not raising taxes on the wealthy or using the central bank to monetize spending on anything except bailing out the banks and subsidizing the financial sector, the government follows a pro-creditor policy. Tax favoritism for the wealthy deepens the budget deficit, forcing governments to borrow more. Paying interest on this debt diverts revenue from being spent on goods and services. This fiscal austerity shrinks markets, reducing tax revenue to the brink of default. This enables bondholders to treat the government in the same way that banks treat a bankrupt family, forcing the debtor to sell off assets – in this case the public domain as if it were the family silver, as Britain’s Prime Minister Harold MacMillan characterized Margaret Thatcher’s privatization sell-offs.

In an Orwellian doublethink twist this privatization is done in the name of free markets, despite being imposed by global financial institutions whose administrators are not democratically elected. The International Monetary Fund (IMF), European Central Bank (ECB) and EU bureaucracy treat governments like banks treat homeowners unable to pay their mortgage: by foreclosing. Greece, for example, has been told to start selling off prime tourist sites, ports, islands, offshore gas rights, water and sewer systems, roads and other property.

Sovereign governments are, in principle, free of such pressure. That is what makes them sovereign. They are not obliged to settle public debts and budget deficits by asset selloffs. They do not need to borrow more domestic currency; they can create it. This self-financing keeps the national patrimony in public hands rather than turning assets over to private buyers, or having to borrow from banks and bondholders.


Why the Fiscal Squeeze Imposes Needless Austerity

The financial sector promises that privatizing roads and ports, water and sewer systems, bus and railroad lines (on credit, of course) is more efficient and will lower the prices charged for their services. The reality is that the new buyers put up rent-extracting tollbooths on the infrastructure being sold. Their break-even costs include the high salaries and bonuses they pay themselves, as well as interest and dividends to their creditors and backers, spending on stock buy-backs and political lobbying.

Public borrowing creates a dependency that shifts economic planning to Wall Street and other financial centers. When voters resist, it is time to replace democracy with oligarchy. “Technocratic” rule replaces that of elected officials. In Europe the IMF, ECB and EU troika insists that all debts must be paid, even at the cost of austerity, depression, unemployment, emigration and bankruptcy. This is to be done without violence where possible, but with police-state practices when grabbers find it necessary to quell popular opposition.

Financializing the economy is depicted as a natural way to gain wealth – by taking on more debt. Yet it is hard to think of a more highly politicized policy, shaped as it is by tax rules that favor bankers. It also is self-terminating, because when public debt grows to the point where investors (“the market”) no longer believe that it can be repaid, creditors mount a raid (the military analogy is appropriate) by “going on strike” and not rolling over existing bonds as they fall due. Bond prices fall, yielding higher interest rates, until governments agree to balance the budget by voluntary pre-bankruptcy privatizations.

Selling Saved-up Treasury Bonds to Fund Public Programs is Like New Deficit Borrowing

If the aim of America’s military spending around the world is to prepare for future warfare, why not aim at saving up a fund of $10 trillion or even $30 trillion in advance, as with Social Security, so that we will have the money to pay for it?

The answer is that selling saved-up Treasury bills to finance Social Security, military spending or any other program has the same monetary and price effect as issuing new Treasury bills. The impact on financial markets – and on the private sector’s holding of government debt – by paying Social Security out of past savings – that is, by selling the Treasury securities in which Social Security funds are invested – is much like borrowing by selling new securities. It makes little difference whether the Treasury sells newly printed IOUs, or sells bonds that it has been accumulating in a special fund. The effect is to increase public debt owed to the financial sector.

If the savings are to be invested in Treasury bonds (as is the case with Social Security), will this pay for tax cuts elsewhere in the budget? If so, will these cuts be for the wealthy 1% or the 99%? Or, will the savings be invested in infrastructure, or turned over to states and cities to help balance their budget shortfalls and underfunded pension plans?

Another problem concerns who should pay for this pre-saving. The taxes needed to pre-fund a savings build-up siphon off income from somewhere in the economy. How much will the economy shrink by diverting income from being spent on goods and services? And whose income will taxed? These questions illustrate how politically self-interested it is to single out taxing wages to save for Social Security in contrast to war-making and beach-house rebuilding.

Government budgets usually are designed to be in balance under normal peacetime conditions, so most public debt has been brought into being by war (prior to today’s financial war of slashing taxes on the wealthy). Adam Smith’s Wealth of Nations (Book V) traced how each new British bond issue to raise funds for a military action had a dedicated tax to pay its interest charges. The accumulation of such war debts thus raised the cost of living and hence the break-even price of labor. To prevent this from undercutting of British competitiveness, Smith urged that wars be waged on a pay-as-you-go basis – by full taxation rather than by borrowing and entailing interest payments and taxes (as the debt itself rarely was amortized). Smith thought that populations should feel the cost of war directly and immediately, presumably leading them to be vigilant in checking grandiose projects of empire.

The United States issued fiat greenback currency to pay for much of its Civil War, but also issued bonds. In analyzing this war finance the Canadian-American astronomer and monetary theorist Simon Newcomb pointed out that all wars must be paid for in the form of tangible material and lives by the generation that fights them. Paying for the war by borrowing from bondholders, he explained, involved levying taxes to pay the interest. The effect was to transfer income from the Western states (taxpayers) to bondholders in the East.

In the case of Social Security today the beneficiary of government debt is still the financial sector. The economy must provide the housing, food, health care, transportation and clothing to enable retirees to live normal lives. This economic surplus can be paid for either out of taxation, new money creation or borrowing. But instead of “the West,” the major payers of the Social Security tax are wage earners across the nation. Taxing labor shrinks markets and forces the economy into austerity.

Quantitative Easing as Free Money Creation – To Subsidize the Big Banks

The Federal Reserve’s three waves of Quantitative Easing since 2008 show how easy it is to create free money. Yet this has been provided only to the largest banks, not to strapped homeowners or industry. An immediate $2 trillion in “cash for trash” took the form of the Fed creating new bank-reserve credit in exchange for mortgage-backed securities valued far above market prices. QE2 provided another $800 billion in 2011-12. The banks used this injection of credit for interest rate arbitrage and exchange rate speculation on the currencies of Brazil, Australia and other high-interest-rate economies. So nearly all the Fed’s new money went abroad rather than being lent out for investment or employment at home.

U.S. Government debt was run up mainly to re-inflate prices for packaged bank mortgages, and hence real estate prices. Instead of alleviating private-sector debt by writing down mortgages in line with the homeowners’ ability to pay, the Federal Reserve and Treasury created money to support property prices – to push the banking system’s balance sheets back above negative net worth. The Fed’s QE3 program in 2012-13 created money to buy mortgage-backed securities each month, to provide banks with money to lend to new property buyers.

For the economy at large, the debts were left in place. Yet commentators focused only on government debt. In a double standard, they accused budget deficits of inflating wages and consumer prices, yet the explicit aim of quantitative easing was to support asset prices. Inflating asset prices on credit is deemed to be good for the economy, despite loading it down with debt. But public spending into the “real” economy, raising employment levels and sustaining consumer spending, is deemed bad – except when this is financed by personal borrowing from the banks. So in each case, increasing bank profits is the standard by which fiscal policy is to be judged!

The result is a policy asymmetry that is opposite from what most epochs have deemed fair or helpful to economic growth. Bankers and bondholders insist that the public sector borrow from them, blocking the government’s power to self-finance its operations – with one glaring exception. That exception occurs when the banks themselves need free money creation. The Fed provided nearly free credit to the banks under QE2, and Chairman Ben Bernanke promised to continue this policy until such time as the unemployment rate drops to 6.5%. The pretense is that low interest rates spur employment, but the most pressing aim is to provide easy credit to revive borrowing and bid asset prices back up.

Fiscal Deflation on Top of Debt Deflation

The main financial problem with funding war occurs after the return to normalcy, when creditors press for budget surpluses to roll back the public debt that has been run up. This imposes fiscal austerity, reducing wages and commodity prices relative to the debts that are owed. Consumer spending shrinks and prices decline as governments spend less, while higher taxes withdraw revenue. This is what is occurring in today’s financial war, much as it has in past military postwar returns to peace.

Governments have the power to resist this deflationary policy. Like commercial banks, they can create money on their computer keyboards. Indeed, since 2008 the government has created debt to support the Finance, Insurance and Real Estate (FIRE) sector more than the “real” production and consumption economy.

In contrast to public spending for goods and services (or social programs that increase market demand), most of the bank credit that led to the 2008 financial collapse was created to finance the purchase property already in place, stocks and bonds already issued, or companies already in existence. The effect has been to load down the economy with mortgages, bonds and bank debt whose carrying charges eat into spending on current output. The $13 trillion bank subsidy since 2008 (to enable banks to earn their way out of negative equity) brings us back to the question of why taxes should be levied on the 99% to pre-save for Social Security and Medicare, but not for the bank bailout.

Current tax policy encourages financial and rent extraction that has become the major economic problem of our epoch. Industrial productivity continues to rise, but debt is growing even more inexorably. Instead of fueling economic growth, this of credit/debt threatens to absorb the economic surplus, plunging the economy into austerity, debt deflation and negative equity.

So despite the fact that the financial system is broken, it has gained control over public policy to sustain and even obtain tax favoritism for a dysfunctional overgrowth of bank credit. Unlike the progress of science and technology, this debt is not part of nature. It is a social construct. The financial sector has politicized it by pressing to privatize economic rent rather than collect it as the tax base. This financialization of rent-extracting opportunities does not reflect a natural or inevitable evolution of “the market.” It is a capture of market structures and fiscal policy. Bank lobbyists have campaigned to shift the economic arena to the political sphere of lawmaking and tax policy, with side battlegrounds in the mass media and universities to capture the hearts and minds of voters to believe that the quickest and most efficient way to build up wealth is by bank credit and debt leverage.

Budget Deficits as an Antidote to Austerity

Public debts everywhere are growing, as taxes only cover part of public spending. The least costly way to finance this expenditure is to issue money – the paper currency and coins we carry in our pockets. Holders of this currency technically are creditors to the government – and to society, which accepts this money in payment. Yet despite being nominally a form of public debt, this money serves as public capital inasmuch as it is not normally expected to be repaid. This government money does not bear interest, and may be thought of as “equity capital” or “equity money,” and hence part of the economy’s net worth.

If taxes did fully cover government spending, there would be no budget deficit – or new public money creation. Government budget deficits pump money into the economy. Conversely, running a budget surplus retires the public debt or currency outstanding. This deflationary effect occurred in the late 19th-century, causing monetary deflation that plunged the U.S. economy into depression. Likewise when President Bill Clinton ran a budget surplus late in his administration, the economy relied on commercial banks to supply credit to use as the means of payment, charging interest for this service. As Stephanie Kelton summarizes this historical experience:

The federal government has achieved fiscal balance (even surpluses) in just seven periods since 1776, bringing in enough revenue to cover all of its spending during 1817-21, 1823-36, 1852-57, 1867-73, 1880-93, 1920-30 and 1998-2001. We have also experienced six depressions. They began in 1819, 1837, 1857, 1873, 1893 and 1929.

Do you see the correlation? The one exception to this pattern occurred in the late 1990s and early 2000s, when the dot-com and housing bubbles fueled a consumption binge that delayed the harmful effects of the Clinton surpluses until the Great Recession of 2007-09.

When taxpayers pay more to the government than the economy receives in public spending, the effect is like paying banks more than they provide in new credit. The debt volume is reduced (increasing the reported savings rate). The resulting austerity is favorable to the financial sector but harmful to the rest of the economy.

Most people think of money as a pure asset (like a coin or a $10 dollar bill), not as being simultaneously a public debt. But to an accountant, a balance sheet always balances: Assets = Liabilities + Net Worth. This liability-side ambivalence is confusing to most people. It takes some time to think in terms of offsetting assets and liabilities as mirror images of each other. Much as cosmologists assume that the universe is symmetrical – with positively charged matter having an anti-matter counterpart somewhere at the other end – so accountants view the money in our pocket as being created by the government’s deficit spending. Holders of the Federal Reserve’s paper currency technically can redeem it, but they will simply get paid in other denominations of the same currency.

The word “redeem” comes from settling debts. This was the purpose for which money first came into being. Governments redeem money by accepting it for tax payment. In addition to issuing paper currency, the Federal Reserve injects money into the economy by writing checks electronically. The recipients (usually banks selling Treasury bonds or, more recently, packages of mortgage loans) gain a deposit at the central bank. This is the kind of deposit that was created by the above-mentioned $13 trillion in new debt that the government turned over to Wall Street after the September 2008 crisis. The price impact was felt in financial asset markets, not in prices for goods and services or labor’s wages.

This Federal Reserve and Treasury credit was not counted as part of the government’s operating deficit. Yet it increased public debt, without being spent on “real” GDP. The banks used this money mainly to gamble on foreign exchange and interest-rate arbitrage as noted above, to buy smaller banks (helping make themselves Too Big To Fail), and to keep paying their managers high salaries and bonuses.

This monetization of debt shows how different government budgets are from family budgets. Individuals must save to pay for retirement or other spending. They cannot print their own money, or tax others. But governments do not need to “save” (or tax) to pay for their spending. Their ability to create money means that they do not need to save in advance to pay for wars, Social Security or other needs.

Keynesian Deficit Spending vs. Bailing out Wall Street to Keep the Debt Overhead in Place

There are two kinds of markets: hiring labor to produce goods and services in the “real” economy, and transactions in financial assets and property claims in the FIRE sector. Governments can run budget deficits by financing either of these two spheres. Since President Franklin Roosevelt’s WPA programs in the 1930s, along with his public infrastructure investment in roads, dams and other construction – and military arms spending after World War II broke out – “Keynesian” spending on goods and services has been used to hire labor or pay for social programs. This pumps money into the economy via the GDP-type transactions that appear in the National Income and Product Accounts. It is not inflationary when unemployment exists.

However, the debt that characterized the Paulson-Geithner bailout of Wall Street was created not to spend on goods and services, but to buy (or take liability for) mortgages and bank loans, insurance default bets and arbitrage gambles. The aim was to subsidize financial losses while keeping the debt overhead in place, so that banks and other financial institutions could “earn their way” out of negative net worth, at the economy’s expense. The idea was that they could start lending again to prevent real estate prices from falling further, saving them from having to write down their debt claims to bring levels back down within the ability to be paid.
The Ideological Crisis Underlying Today’s Tax and Financial Policy

From antiquity and for thousands of years, land, natural resources and monopolies, seaports and roads were kept in the public domain. In more recent times railroads, subway lines, airlines, and gas and electric utilities were made public. The aim was to provide their basic services at cost or at subsidized prices rather than letting them be privatized into rent-extracting opportunities. The Progressive Era capped this transition to a more equitable economy by enacting progressive income and wealth taxes.

Economies were liberating themselves from the special privileges that European feudalism and colonialism had granted to favored insiders. The aim of ending these privileges – or taxing away economic rent where it occurs naturally, as in the land’s site value and natural resource rent – was to lower the costs of living and doing business. This was expected to make progressive economies more competitive, obliging other countries to follow suit or be rendered obsolete. The era of what was considered to be socialism in one form or another seemed to be at hand – rising role of the public sector as part and parcel of the evolution of technology and prosperity.

But the landowning and financial classes fought back, seeking to expunge the central policy conclusion of classical economics: the doctrine that free-lunch economic rent should serve as the tax base for economies seeking to be most efficient and fair. Imbued with academic legitimacy by the University of Chicago (which Upton Sinclair aptly named the University of Standard Oil) the new post-classical economics has adopted Milton Friedman’s motto: “There Is No Such Thing As A Free Lunch” (TINSTAAFL). If it is not seen, it has less likelihood of being taxed.

The political problem faced by rentiers – the “idle rich” siphoning off most of the economy’s gains for themselves – is to convince voters to agree that labor and consumers should be taxed rather than the financial gains of the wealthiest 1%. How long can they defer people from seeing that making interest tax-exempt pushes the government’s budget further into deficit? To free financial wealth and asset-price gains from taxes – while blocking the government from financing its deficits by its own public option for money creation – the academics sponsored by financial lobbyists hijacked monetary theory, fiscal policy and economic theory in general. On seeming grounds of efficiency they claimed that government no longer should regulate Wall Street and its corporate clients. Instead of criticizing rent seeking as in earlier centuries, they depicted government as an oppressive Leviathan for using its power to protect markets from monopolies, crooked drug companies, health insurance companies and predatory finance.

This idea that a “free market” is one free for Wall Street to act without regulation can be popularized only by censoring the history of economic thought. It would not do for people to read what Adam Smith and subsequent economists actually taught about rent, taxes and the need for regulation or public ownership. Academic economics is turned into an Orwellian exercise in doublethink, designed to convince the population that the bottom 99% should pay taxes rather than the 1% that obtain most interest, dividends and capital gains. By denying that a free lunch exists, and by confusing the relationship between money and taxes, they have turned the economics discipline and much political discourse into a lobbying effort for the 1%.

Lobbyists for the 1% frame the fiscal question in terms of “How can we make the 99% pay for their own social programs?” The implicit follow-up is, “so that we (the 1%) don’t have to pay?” This is how the Social Security system came to be “funded” and then “underfunded.” The most regressive tax of all is the FICA payroll tax at 15.3% of wages up to about $105,000. Above that, the rich don’t have to contribute. This payroll tax exceeds the income tax paid by many blue-collar families. The pretense is that not taxing these free lunchers will make economies more competitive and pull them out of depression. The reality is the opposite: Instead of taxing the wealthy on their free lunch, the tax burden raises the cost of living and doing business. This is a major reason why the U.S. economy is being de-industrialized today.

The key question is what the 1% do with their revenue “freed” from taxes. The answer is that they lend it out to indebt the 99%. This polarizes the economy between creditors and debtors. Over the past generation the wealthiest 1% have rewritten the tax laws to a point where they now receive an estimated 66% – two thirds – of all returns to wealth (interest, dividends, rents and capital gains), and a reported 93% of all income gains since the Wall Street bailout of September 2008.

They have used this money to finance the election campaigns of politicians committed to shifting taxes onto the 99%. They also have bought control of the major news media that shape peoples’ understanding of what is happening. And as Thorstein Veblen described nearly a century ago, businessmen have become the heads most universities and directed their curriculum along “business friendly” lines.

The clearest way to analyze any financial system is to ask Who/Whom. That is because financial systems are basically a set of debts owed to creditors. In today’s neo-rentier economy the bottom 99% (labor and consumers) owe the 1% (bondholders, stockholders and property owners). Corporate business and government bodies also are indebted to this 1%. The degree of financial polarization has sharply accelerated as the 1% are making their move to indebt the 99% – along with industry, state, local and federal government – to the point where the entire economic surplus is owed as debt service. The aim is to monopolize the economy, above all the money-creating privilege of supplying the credit that the economy needs to grow and transact business, enabling them to extract interest and other fees for this privilege.

The top 1% have nearly succeeded in siphoning off the entire surplus for themselves, receiving 93% of U.S. income growth since September 2008. Their control over the political process has enabled them to use each new financial crisis to strengthen their position by forcing companies, states and localities to relinquish property to creditors and financial investors. So after monopolizing the economic surplus, they now are seeking to transfer to themselves the economic infrastructure, land and natural resources, and any other asset on which a rent-extracting tollbooth can be placed.

The situation is akin to that of medieval Europe in the wake of the Nordic invasions. The supra-national force of Rome in feudal times is now situated in Washington, with Christianity replaced by the Washington Consensus wielded via the IMF, World Bank, WTO and its satellite institutions such as the European Central Bank, backed by the moral and ideological role academic economists rather than the Church. And on the new financial battlefield, Wall Street underwriters have used the crisis as an opportunity to press for privatization. Chicago’s strong Democratic political machine sold rights to install parking meters on its sidewalks, and has tried to turn its public roads into privatized toll roads. And the city’s Mayor Rahm Emanuel has used privatization of its airport services to break labor unionization, Thatcher-style. The class war is back in business, with financial tactics playing a leading role barely anticipated a century ago.

This monopolization of property is what Europe’s medieval military conquests sought to achieve, and what its colonization of foreign continents replicated. But whereas it achieved this originally by military conquest of the land, today’s 1% do it l by financializing the economy (although the military arm of force is not absent, to be sure, as the world saw in Chile after 1973).

The financial quandary confronting us

The economy’s debt overhead has grown so large that not everyone can be paid. Rising default rates pose the question age-old question of Who/Whom. The answer almost always is that big fish eat little fish. Big banks (too big to fail) are eating little banks, while the 1% try to take the lion’s share for themselves by annulling public and corporate debts owed to the 99%. Their plan is to downgrade Social Security and Medicare savings to “entitlements,” as if it is a matter of sound fiscal choice not to pay low-income payers whilerentiers at the top re-christen themselves “job creators,” as if they have made their gains by helping wage-earners rather than waging war against them.

The problem is not Social Security, which can be paid out of normal tax revenue, as in Germany’s pay-as-you-go system. This fiscal problem – untaxing real estate, oil and gas, natural resources, monopolies and the banks – has been depicted as financial – as if one needs to save in advance by a special tax to lend to the government to cut taxes on the 99%.

The real pension cliff is with corporate, state and local pension plans, which are being underfunded and looted by financial managers. The shortfall is getting worse as the downturn reduces local tax revenues, leaving states and cities unable to fund their programs, to invest in new public infrastructure, or even to maintain and repair existing investments. Public transportation in particular is suffering, raising user fees to riders in order to pay bondholders. But it is mainly retirees who are being told to sacrifice. (The sanctimonious verb is “share” in the sacrifice, although this evidently does not apply to the 1%.)

The bank lobby would like the economy to keep trying to borrow its way out of debt and thus dig itself deeper into a financial hole that puts yet more private and public property at risk of default and foreclosure. The idea is for the government to “stabilize” the financial system by bailing out the banks – that is, doing for them what it has not been willing to do for recipients of Social Security and Medicare, or for states and localities no longer receiving revenue sharing, or for homeowners in negative equity suffering from exploding interest rates even while bank borrowing costs from the Fed have plunged. The dream is that the happy Greenspan financial bubble can be recovered, making everyone rich again, if only they will debt-leverage to bid up real estate, stock and bond prices and create new capital gains.

Realizing this dream is the only way that pension funds can pay retirees. They will be insolvent if they cannot make their scheduled 8+%, giving new meaning to the term “fictitious capital.” And in the real estate market, prices will not soar again until speculators jump back in as they did prior to 2008. If student loans are not annulled, graduates face a lifetime of indentured servitude. But that is how much of colonial America was settled, after all – working off the price of their liberty, only to be plunged into the cauldron of vast real estate speculations and fortunes-by-theft on which the Republic was founded (or at least the greatest American fortunes). It was imagined that such bondage belonged only to a bygone era, not to the future of the West. But we may now look back to that era for a snapshot of our future.

The financial plan is for the government is to supply nearly free credit to the banks, so that they can to lend debtors enough – at the widest interest-rate markups in recent memory (what banks charge borrowers and credit-card users over their less-than-1% borrowing costs) – to pay down the debts that were run up before 2008.

This is not a program to increase market demand for the products of labor. It is not the kind of circular flow that economists have described as the essence of industrial capitalism. It is a financial rake-off of a magnitude such as has not existed since medieval European times, and the last stifling days of the oligarchic Roman Empire two thousand years ago.

Imagining that an economy can be grounded on these policies will further destabilize the economy rather than alleviate today’s debt deflation. But if the economy is saved, the banks cannot be. This is why the Obama Administration has chosen to save the banks, not the economy. The Fed’s prime directive is to keep interest rates low – to revive lending not to finance new business investment to produce more, but simply to inflate the asset prices that back the bank loans that constitute bank reserves. It is the convoluted dream of a new Bubble Economy – or more accurately a new Great Giveaway.

Here’s the quandary: If the Fed keeps interest rates low, how are corporate, state and local pension plans to make the 8+% returns needed to pay their scheduled pensions? Are they to gamble more with hedge funds playing Casino Capitalism?

On the other hand, if interest rates rise, this will reduce the capitalization multiple at which banks lend against current rental income and profits. Higher interest rates will lower prices for real estate, corporate stocks and bonds, pushing the banks (and pension funds) even deeper into negative equity.

So something has to give. Either way, the financial system cannot continue along its present path. Only debt write-offs will “free” markets to resume spending on goods and services. And only a shift of taxes onto rent-yielding property and tollbooths, finance and monopolies will save prices from being loaded down with extractive overhead charges and refocus lending to finance production and employment. Unless this is done, there is no way the U.S. economy can become competitive in international markets, except of course for military hardware and intellectual property rights for escapist cultural artifacts.

The solution for Social Security, Medicare and Medicaid is to de-financialize them. Treat them like government programs for military spending, beachfront rebuilding and bank subsidies, and pay their costs out of current tax revenue and new money creation by central banks doing what they were founded to do.

Politicians shy away from confronting this solution mainly because the financial sector has sponsored a tunnel vision that ignores the role of debt, money, and the phenomena of economic rent, debt leverage and asset-price inflation that have become the defining characteristics of today’s financial crisis. Government policy has been captured to try and save – or at least subsidize – a financial system that cannot be saved more than temporarily. It is being kept on life support at the cost of shrinking the economy – while true medical spending for real life support is being cut back for much of the population.

The economy is dying from a financial respiratory disease, or what the Physiocrats would have called a circulatory disorder. Instead of freeing the economy from debt, income is being diverted to pay credit card debt and mortgage debts. Students without jobs remain burdened with over $1 trillion of student debt, with the time-honored safety valve of bankruptcy closed off to them. Many graduates must live with their parents as marriage rates and family formation (and hence, new house-buying) decline. The economy is dying. That is what neoliberalism does.

Now that the debt build-up has run its course, the banking sector has put its hope in gambling on mathematical probabilities via hedge fund capitalism. This Casino Capitalist has become the stage of finance capitalism following Pension Fund capitalism – and preceding the insolvency stage of austerity and property seizures.

The open question now is whether neofeudalism will be the end stage. Austerity deepens rather than cures public budget deficits. Unlike past centuries, these deficits are not being incurred to wage war, but to pay a financial system that has become predatory on the “real” economy of production and consumption. The collapse of this system is what caused today’s budget deficit. Instead of recognizing this, the Obama Administration is trying to make labor pay. Pushing wage-earners over the “fiscal cliff” to make them pay for Wall Street’s financial bailout (sanctimoniously calling their taxes “user fees”) can only shrink of market more, pushing the economy into a fatal combination of tax-ridden and debt-ridden fiscal and financial austerity.

The whistling in the intellectual dark that central bankers call by the technocratic term “deleveraging” (paying off the debts that have been run up) means diverting yet more income to pay the financial sector. This is antithetical to resuming economic growth and restoring employment levels. The recent lesson of European experience is that despite austerity, debt has risen from 381% of GDP in mid-2007 to 417% in mid—2012. That is what happens when economies shrink: debts mount up at arrears (and with stiff financial penalties).

But even as economies shrink, the financial sector enriches itself by turning its debt claims – what 19th-century economists called “fictitious capital” before it was called finance capital – into a property grab. This makes an unrealistic debt overhead – unrealistic because there is no way that it can be paid under existing property relations and income distribution – into a living nightmare. That is what is happening in Europe, and it is the aim of Obama Administration of Tim Geithner, Ben Bernanke, Erik Holder et al. They would make America look like Europe, wracked by rising unemployment, falling markets and the related syndrome of adverse social and political consequences of the financial warfare waged against labor, industry and government together. The alternative to the road to serfdom – governments strong enough to protect populations against predatory finance – turns out to be a detour along the road to debt peonage and neofeudalism.

So we are experiencing the end of a myth, or at least the end of an Orwellian rhetorical patter talk about what free markets really are. They are not free if they are to pay rent-extractors rather than producers to cover the actual costs of production. Financial markets are not free if fraudsters are not punished for writing fictitious junk mortgages and paying ratings agencies to sell “opinions” that their clients’ predatory finance is sound wealth creation. A free market needs to be regulated from fraud and from rent seeking.

The other myth is that it is inflationary for central banks to monetize public spending. What increases prices is building interest and debt service, economic rent and financial charges into the cost of living and doing business. Debt-leveraging the price of housing, education and health care to make wage-earners pay over two-thirds of their income to the FIRE sector, FICA wage withholding and other taxes falling on labor are responsible for de-industrializing the economy and making it uncompetitive.

Central bank money creation is not inflationary if it funds new production and employment. But that is not what is happening today. Monetary policy has been hijacked to inflate asset prices, or at least to stem their decline, or simply to give to the banks to gamble. “The economy” is less and less the sphere of production, consumption and employment; it is more and more a sphere of credit creation to buy assets, turning profits and income into interest payments until the entire economic surplus and repertory of property is pledged for debt service.

To celebrate this as a “postindustrial society” as if it is a new kind of universe in which everyone can get rich on debt leveraging is a deception. The road leading into this trap has been baited with billions of dollars of subsidized junk economics to entice voters to act against their interests. The post-classical pro-rentier financial narrative is false – intentionally so. The purpose of its economic model is to make people see the world and act (or invest their money) in a way so that its backers can make money off the people who follow the illusion being subsidized. It remains the task of a new economics to revive the classical distinction between wealth and overhead, earned and unearned income, profit and rentier income – and ultimately between capitalism and feudalism.

Notes.
[1] No such benefits were given to homeowners whose real estate fell into negative equity. For the few who received debt write-downs to current market value, the credit was treated as normal income and taxed!

[2] Philip Aldrick, “Loss of income caused by banks as bad as a ‘world war’, says BoE’s Andrew Haldane,” The Telegraph, December 3, 2012. Mr. Haldane is the Bank’s executive director for financial stability.