How Today’s Fiscal Austerity is Reminiscent of World War I’s Economic Misunderstandings
by MICHAEL HUDSON
When World War I broke out in August 1914, economists on both sides forecast that hostilities could not last more than about six months. Wars had grown so expensive that governments quickly would run out of money. It seemed that if Germany could not defeat France by springtime, the Allied and Central Powers would run out of savings and reach what today is called a fiscal cliff and be forced to negotiate a peace agreement.
But the Great War dragged on for four destructive years. European governments did what the United States had done after the Civil War broke out in 1861 when the Treasury printed greenbacks. They paid for more fighting simply by printing their own money. Their economies did not buckle and there was no major inflation. That would happen only after the war ended, as a result of Germany trying to pay reparations in foreign currency. This is what caused its exchange rate to plunge, raising import prices and hence domestic prices. The culprit was not government spending on the war itself (much less on social programs).
But history is written by the victors, and the past generation has seen the banks and financial sector emerge victorious. Holding the bottom 99% in debt, the top 1% are now in the process of subsidizing a deceptive economic theory to persuade voters to pursue policies that benefit the financial sector at the expense of labor, industry, and democratic government as we know it.
Wall Street lobbyists blame unemployment and the loss of industrial competitiveness on government spending and budget deficits – especially on social programs – and labor’s demand to share in the economy’s rising productivity. The myth (perhaps we should call it junk economics) is that (1) governments should not run deficits (at least, not by printing their own money), because (2) public money creation and high taxes (at lest on the wealthy) cause prices to rise. The cure for economic malaise (which they themselves have caused), is said to be less public spending, along with more tax cuts for the wealthy, who euphemize themselves as “job creators.” Demanding budget surpluses, bank lobbyists promise that banks can provide the economy with enough purchasing power to grow. Then, when this ends in crisis, they insist that austerity can squeeze out enough income to enable private-sector debts to be paid.
The reality is that when banks load the economy down with debt, this leaves less to spend on domestic goods and services while driving up housing prices (and hence the cost of living) with reckless credit creation on looser lending terms. Yet on top of this debt deflation, bank lobbyists urge fiscal deflation: budget surpluses rather than pump-priming deficits. The effect is to further reduce private-sector market demand, shrinking markets and employment. Governments fall deeper into distress, and are told to sell off land and natural resources, public enterprises, and other assets. This creates a lucrative market for bank loans to finance privatization on credit. This explains why financial lobbyists back the new buyers’ right to raise the prices they charge for basic needs, creating a united front to endorse rent extraction. The effect is to enrich the financial sector owned by the 1% in ways that indebt and privatize the economy at large – individuals, business and the government itself.
This policy was exposed as destructive in the late 1920s and early 1930s when John Maynard Keynes, Harold Moulton and a few others countered the claims of Jacques Rueff and Bertil Ohlin that debts of any magnitude could be paid if governments would impose deep enough austerity and suffering. This is the doctrine adopted by the International Monetary
Fund to impose on Third World debtors since the 1960s, and by European neoliberals defending creditors imposing austerity on Ireland, Greece, Spain and Portugal.
This pro-austerity mythology aims to distract the public from asking why peacetime governments can’t simply print the money they need. Given the option of printing money instead of levying taxes, why do politicians only create new spending power for the purpose of waging war and destroying property, not to build or repair bridges, roads and other public infrastructure? Why should the government tax employees for future retirement payouts, but not Wall Street for similar user fees and financial insurance to build up a fund to pay for future bank over-lending crises? For that matter, why doesn’t the U.S. Government print the money to pay for Social Security and medical care, just as it created new debt for the $13 trillion post-2008 bank bailout? (I will return to this question below.)
The answer to these questions has little to do with markets, or with monetary and tax theory. Bankers claim that if they have to pay more user fees to pre-fund future bad-loan claims and deposit insurance to save the Treasury or taxpayers from being stuck with the bill, they will have to charge customers more – despite their current record profits, which seem to grab everything they can get. But they support a double standard when it comes to taxing labor.
Shifting the tax burden onto labor and industry is achieved most easily by cutting back public spending on the 99%. That is the root of the December 2012 showdown over whether to impose the anti-deficit policies proposed by the Bowles-Simpson commission of budget cutters whom President Obama appointed in 2010. Shedding crocodile tears over the government’s failure to balance the budget, banks insist that today’s 15.3% FICA wage withholding be raised – as if this will not raise the break-even cost of living and drain the consumer economy of purchasing power. Employers and their work force are told to save in advance for Social Security or other public programs. This is a disguised income tax on the bottom 99%, whose proceeds are used to reduce the budget deficit so that taxes can be cut on finance and the 1%. To paraphrase Leona Helmsley’s quip that “Only the little people pay taxes,” the post-2008 motto is that only the 99% have to suffer losses, not the 1% as debt deflation plunges real estate and stock market prices to inaugurate a Negative Equity economy while unemployment rates soar.
There is no more need to save in advance for Social Security than there is to save in advance to pay for war. Selling Treasury bonds to pay for retirees has the identical monetary and fiscal effect of selling newly printed securities. It is a charade – to shift the tax burden onto labor and industry. Governments need to provide the economy with money and credit to expand markets and employment. They do this by running budget deficits, and this can be done by creating their own money. That is what banks oppose, accusing it of leading to hyperinflation rather than help economies grow.
Their motivation for this wrong accusation is self-serving and their logic is deceptive. Bankers always have fought to block government from creating its own money – at least under normal peacetime conditions. For many centuries, government bonds were the largest and most secure investment for the financial elites that hold most savings. Investment bankers and brokers monopolized public finance, at substantial underwriting commissions. The market for stocks and corporate bonds was rife with fraud, dominated by insiders for the railroads and great trusts being organized by Wall Street, and the canal ventures organized by French and British stockbrokers.
However, there was little alternative to governments creating their own money when the costs of waging an international war far exceeded the volume of national savings or tax revenue available. This obvious need quieted the usual opposition mounted by bankers to limit the public monetary option. It shows that governments can do more under force majeur emergencies than under normal conditions. And the September 2008 financial crisis provided an opportunity for the U.S. and European governments to create new debt for bank bailouts. This turned out to be as expensive as waging a war. It was indeed a financial war. Banks already had captured the regulatory agencies to engage in reckless lending and a wave of fraud and corruption not seen since the 1920s. And now they were holding economies hostage to a break in the chain of payments if they were not bailed out for their speculative gambles, junk mortgages and fraudulent loan packaging.
Their first victory was to disable the ability – or at least the willingness – of the Treasury, Federal Reserve and Comptroller of the Currency to regulate the financial sector. Goldman Sachs, Citicorp and their fellow Wall Street giants hold veto power the appointment of key administrators at these agencies. They used this beachhead to weed out nominees who might not favor their interests, preferring ideological deregulators in the stripe of Alan Greenspan and Tim Geithner. As John Kenneth Galbraith quipped, a precondition for obtaining a central bank post is tunnel vision when it comes to understanding that governments can create their credit as readily as banks can. What is necessary is for one’s political loyalties to lie with the banks.
In the post-2008 financial wreckage it took only a series of computer keystrokes for the U.S. Government to create $13 trillion in debt to save banks from suffering losses on their reckless real estate loans (which computer models pretended would make banks so rich that they could pay their managers enormous salaries, bonuses and stock options), insurance bets gone bad (underpricing risk to win business to pay their managers enormous salaries and bonuses), arbitrage gambles and outright fraud (to give the illusion of earnings justifying enormous salaries, bonuses and stock options). The $800 billion Troubled Asset Relief Program (TARP) and $2 trillion of Federal Reserve “cash for trash” swaps enabled the banks to continue their remuneration of executives and bondholders with hardly a hiccup – while incomes and wealth plunged for the remaining 99% of Americans.
A new term,
Casino Capitalism, was coined to describe the transformation that finance capitalism was undergoing in the post-1980 era of deregulation that opened the gates for banks to do what governments hitherto did in time of war: create money and new public debt simply by “printing it” – in this case, electronically on their computer keyboards.
Taking the insolvent
Fannie Mae and Freddie Mac mortgage financing agencies onto the public balance sheet for $5.2 trillion accounted for over a third of the $13 trillion bailout. This saved their bondholders from having to suffer losses from the fraudulent appraisals on the junk mortgages with which
Countrywide, Bank of America, Citibank and other “too big to fail” banks had stuck them. This enormous debt increase was done without raising taxes. In fact, the Bush administration cut taxes, giving the largest cuts to the highest income and wealth brackets who were its major campaign contributors. Special tax privileges were given to banks so that they could “earn their way out of debt” (and indeed, out of negative equity).[1] The Federal Reserve gave a free line of credit (Quantitative Easing) to the banking system at only 0.25% annual interest by 2011 – that is, one quarter of a percentage point, with no questions asked about the quality of the junk mortgages and other securities pledged as collateral at their full face value, which was far above market price.
This $13 trillion debt creation to save banks from having to suffer a loss was not accused of threatening economic stability. It enabled them to resume paying exorbitant salaries and bonuses, dividends to bondholders and also to pay counterparties on casino-capitalist arbitrage bets. These payments have helped the 1% receive a reported 93% of the gains in income since 2008. The bailout thus polarized the economy, giving the financial sector more power over labor and consumers, industry and the government than has been the case since the late 19th-century Gilded Age.
All this makes today’s financial war much like the aftermath of World War I and countless earlier wars. The effect is to impoverish the losers, appropriate hitherto public assets for the victors, and impose debt service and taxes much like levying tribute. “The financial crisis has been as economically devastating as a world war and may still be a burden on ‘our grandchildren,’” Bank of England official Andrew Haldane recently observed. “‘In terms of the loss of incomes and outputs, this is as bad as a world war.’ he said. The rise in government debt has prompted calls for austerity – on the part of those who did not receive the giveaway. ‘It would be astonishing if people weren’t asking big questions about where finance has gone wrong.’”[2]
But as long as the financial sector is winning its war against the economy at large, it prefers that people believe that There Is No Alternative. Having captured mainstream economics as well as government policy, finance seeks to deter students, voters and the media from questioning whether the financial system really needs to be organized in the way it is. Once such a line of questioning is pursued, people may realize that banking, pension and Social Security systems and public deficit financing do not have to be organized in the way they are. There are better alternatives to today’s road to austerity and debt peonage.
The Financial War Against the Economy at Large
Today’s economic warfare is not the kind waged a century ago between labor and its industrial employers. Finance has moved to capture the economy at large, industry and mining, public infrastructure (via privatization) and now even the educational system. (At over $1 trillion, U.S. student loan debt came to exceed credit-card debt in 2012.) The weapon in this financial warfare is no longer military force. The tactic is to load economies (governments, companies and families) with debt, siphon off their income as debt service and then foreclose when debtors lack the means to pay. Indebting government gives creditors a lever to pry away land, public infrastructure and other property in the public domain. Indebting companies enables creditors to seize employee pension savings. And Indebting labor means that it no longer is necessary to hire strikebreakers to attack union organizers and strikers.
Workers have become so deeply indebted on their home mortgages, credit cards and other bank debt that they fear to strike or even to complain about working conditions. Losing work means missing payments on their monthly bills, enabling banks to jack up interest rates to levels that used to be deemed usurious. So debt peonage and unemployment loom on top of the wage slavery that was the main focus of class warfare a century ago. And to cap matters, credit-card bank lobbyists have rewritten the bankruptcy laws to curtail debtor rights, and the referees appointed to adjudicate disputes brought by debtors and consumers are subject to veto from the banks and businesses that are mainly responsible for inflicting injury.
The aim of financial warfare is not merely to acquire land, natural resources and key infrastructure rents as in military warfare; it is to centralize creditor control over society. In contrast to the promise of democratic reform nurturing a middle class a century ago, we are witnessing a regression to a world of special privilege in which one must inherit wealth in order to avoid debt and job dependency.
The emerging financial oligarchy seeks to shift taxes off banks and their major customers (real estate, natural resources and monopolies) onto labor. Given the need to win voter acquiescence, this aim is best achieved by rolling back everyone’s taxes. The easiest way to do this is to shrink government spending, headed by Social Security, Medicare and Medicaid. Yet these are the programs that enjoy the strongest voter support. This fact has inspired what may be called the Big Lie of our epoch: the pretense that governments can only create money to pay the financial sector, and that the beneficiaries of social programs should be entirely responsible for paying for Social Security, Medicare and Medicaid, not the wealthy. This Big Lie is used to reverse the concept of progressive taxation, turning the tax system into a ploy of the financial sector to levy tribute on the economy at large.
Financial lobbyists quickly discovered that the easiest ploy to shift the cost of social programs onto labor is to conceal new taxes as user fees, using the proceeds to cut taxes for the elite 1%. This fiscal sleight-of-hand was the aim of the 1983 Greenspan Commission. It confused people into thinking that government budgets are like family budgets, concealing the fact that governments can finance their spending by creating their own money. They do not have to borrow, or even to tax (at least, not tax mainly the 99%).
The Greenspan tax shift played on the fact that most people see the need to save for their own retirement. The carefully crafted and well-subsidized deception at work is that Social Security requires a similar pre-funding – by raising wage withholding. The trick is to convince wage earners it is fair to tax them more to pay for government social spending, yet not also to ask the banking sector to pay similar a user fee to pre-save for the next time it itself will need bailouts to cover its losses. Also asymmetrical is the fact that nobody suggests that the government set up a fund to pay for future wars, so that future adventures such as Iraq or Afghanistan will not “run a deficit” to burden the budget. So the first deception is to treat only Social Security and medical care as user fees. The second is to aggravate matters by insisting that such fees be paid long in advance, by pre-saving.
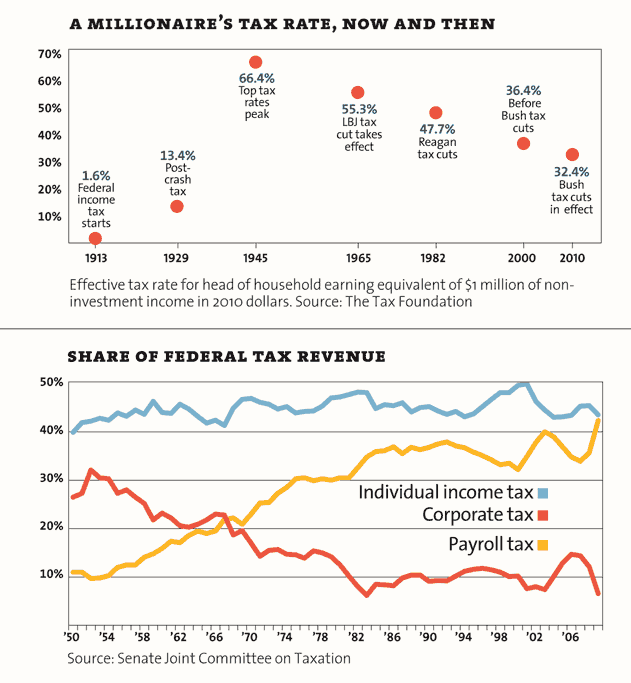
There is no inherent need to single out any particular area of public spending as causing a budget deficit if it is not pre-funded. It is a travesty of progressive tax policy to only oblige workers whose wages are less than (at present) $105,000 to pay this FICA wage withholding, exempting higher earnings, capital gains, rental income and profits. The raison d’être for taxing the 99% for Social Security and Medicare is simply to avoid taxing wealth, by falling on low wage income at a much higher rate than that of the wealthy. This is not how the original U.S. income tax was created at its inception in 1913. During its early years only the wealthiest 1% of the population had to file a return. There were few loopholes, and capital gains were taxed at the same rate as earned income.
The government’s seashore insurance program, for instance, recently incurred a $1 trillion liability to rebuild the private beaches and homes that Hurricane Sandy washed out. Why should this insurance subsidy at below-commercial rates for the wealthy minority who live in this scenic high-risk property be treated as normal spending, but not Social Security? Why save in advance by a special wage tax to pay for these programs that benefit the general population, but not levy a similar “user fee” tax to pay for flood insurance for beachfront homes or war? And while we are at it, why not save another $13 trillion in advance to pay for the next bailout of Wall Street when debt deflation causes another crisis to drain the budget?
But on whom should we levy these taxes? To impose user fees for the beachfront reconstruction would require a tax falling mainly on the wealthy owners of such properties. Their dominant role in funding the election campaigns of the Congressmen and Senators who draw up the tax code suggests why they are able to avoid prepaying for the cost of rebuilding their seashore property. Such taxation is only for wage earners on their retirement income, not the 1% on their own vacation and retirement homes.
By not raising taxes on the wealthy or using the central bank to monetize spending on anything except bailing out the banks and subsidizing the financial sector, the government follows a pro-creditor policy. Tax favoritism for the wealthy deepens the budget deficit, forcing governments to borrow more. Paying interest on this debt diverts revenue from being spent on goods and services. This fiscal austerity shrinks markets, reducing tax revenue to the brink of default. This enables bondholders to treat the government in the same way that banks treat a bankrupt family, forcing the debtor to sell off assets – in this case the public domain as if it were the family silver, as Britain’s Prime Minister Harold MacMillan characterized Margaret Thatcher’s privatization sell-offs.
In an Orwellian doublethink twist this privatization is done in the name of free markets, despite being imposed by global financial institutions whose administrators are not democratically elected. The International Monetary Fund (IMF), European Central Bank (ECB) and EU bureaucracy treat governments like banks treat homeowners unable to pay their mortgage: by foreclosing. Greece, for example, has been told to start selling off prime tourist sites, ports, islands, offshore gas rights, water and sewer systems, roads and other property.
Sovereign governments are, in principle, free of such pressure. That is what makes them sovereign. They are not obliged to settle public debts and budget deficits by asset selloffs. They do not need to borrow more domestic currency; they can create it. This self-financing keeps the national patrimony in public hands rather than turning assets over to private buyers, or having to borrow from banks and bondholders.
Why the Fiscal Squeeze Imposes Needless Austerity
The financial sector promises that privatizing roads and ports, water and sewer systems, bus and railroad lines (on credit, of course) is more efficient and will lower the prices charged for their services. The reality is that the new buyers put up rent-extracting tollbooths on the infrastructure being sold. Their break-even costs include the high salaries and bonuses they pay themselves, as well as interest and dividends to their creditors and backers, spending on stock buy-backs and political lobbying.
Public borrowing creates a dependency that shifts economic planning to Wall Street and other financial centers. When voters resist, it is time to replace democracy with oligarchy. “Technocratic” rule replaces that of elected officials. In Europe the IMF, ECB and EU troika insists that all debts must be paid, even at the cost of austerity, depression, unemployment, emigration and bankruptcy. This is to be done without violence where possible, but with police-state practices when grabbers find it necessary to quell popular opposition.
Financializing the economy is depicted as a natural way to gain wealth – by taking on more debt. Yet it is hard to think of a more highly politicized policy, shaped as it is by tax rules that favor bankers. It also is self-terminating, because when public debt grows to the point where investors (“the market”) no longer believe that it can be repaid, creditors mount a raid (the military analogy is appropriate) by “going on strike” and not rolling over existing bonds as they fall due. Bond prices fall, yielding higher interest rates, until governments agree to balance the budget by voluntary pre-bankruptcy privatizations.
Selling Saved-up Treasury Bonds to Fund Public Programs is Like New Deficit Borrowing
If the aim of America’s military spending around the world is to prepare for future warfare, why not aim at saving up a fund of $10 trillion or even $30 trillion in advance, as with Social Security, so that we will have the money to pay for it?
The answer is that selling saved-up Treasury bills to finance Social Security, military spending or any other program has the same monetary and price effect as issuing new Treasury bills. The impact on financial markets – and on the private sector’s holding of government debt – by paying Social Security out of past savings – that is, by selling the Treasury securities in which Social Security funds are invested – is much like borrowing by selling new securities. It makes little difference whether the Treasury sells newly printed IOUs, or sells bonds that it has been accumulating in a special fund. The effect is to increase public debt owed to the financial sector.
If the savings are to be invested in Treasury bonds (as is the case with Social Security), will this pay for tax cuts elsewhere in the budget? If so, will these cuts be for the wealthy 1% or the 99%? Or, will the savings be invested in infrastructure, or turned over to states and cities to help balance their budget shortfalls and underfunded pension plans?
Another problem concerns who should pay for this pre-saving. The taxes needed to pre-fund a savings build-up siphon off income from somewhere in the economy. How much will the economy shrink by diverting income from being spent on goods and services? And whose income will taxed? These questions illustrate how politically self-interested it is to single out taxing wages to save for Social Security in contrast to war-making and beach-house rebuilding.
Government budgets usually are designed to be in balance under normal peacetime conditions, so most public debt has been brought into being by war (prior to today’s financial war of slashing taxes on the wealthy). Adam Smith’s Wealth of Nations (Book V) traced how each new British bond issue to raise funds for a military action had a dedicated tax to pay its interest charges. The accumulation of such war debts thus raised the cost of living and hence the break-even price of labor. To prevent this from undercutting of British competitiveness, Smith urged that wars be waged on a pay-as-you-go basis – by full taxation rather than by borrowing and entailing interest payments and taxes (as the debt itself rarely was amortized). Smith thought that populations should feel the cost of war directly and immediately, presumably leading them to be vigilant in checking grandiose projects of empire.
The United States issued fiat greenback currency to pay for much of its Civil War, but also issued bonds. In analyzing this war finance the Canadian-American astronomer and monetary theorist Simon Newcomb pointed out that all wars must be paid for in the form of tangible material and lives by the generation that fights them. Paying for the war by borrowing from bondholders, he explained, involved levying taxes to pay the interest. The effect was to transfer income from the Western states (taxpayers) to bondholders in the East.
In the case of Social Security today the beneficiary of government debt is still the financial sector. The economy must provide the housing, food, health care, transportation and clothing to enable retirees to live normal lives. This economic surplus can be paid for either out of taxation, new money creation or borrowing. But instead of “the West,” the major payers of the Social Security tax are wage earners across the nation. Taxing labor shrinks markets and forces the economy into austerity.
Quantitative Easing as Free Money Creation – To Subsidize the Big Banks
The Federal Reserve’s three waves of Quantitative Easing since 2008 show how easy it is to create free money. Yet this has been provided only to the largest banks, not to strapped homeowners or industry. An immediate $2 trillion in “cash for trash” took the form of the Fed creating new bank-reserve credit in exchange for mortgage-backed securities valued far above market prices. QE2 provided another $800 billion in 2011-12. The banks used this injection of credit for interest rate arbitrage and exchange rate speculation on the currencies of Brazil, Australia and other high-interest-rate economies. So nearly all the Fed’s new money went abroad rather than being lent out for investment or employment at home.
U.S. Government debt was run up mainly to re-inflate prices for packaged bank mortgages, and hence real estate prices. Instead of alleviating private-sector debt by writing down mortgages in line with the homeowners’ ability to pay, the Federal Reserve and Treasury
created money to support property prices – to push the banking system’s balance sheets back above negative net worth. The Fed’s QE3 program in 2012-13 created money to buy mortgage-backed securities each month, to provide banks with money to lend to new property buyers.
For the economy at large, the debts were left in place. Yet commentators focused only on government debt. In a double standard, they accused budget deficits of inflating wages and consumer prices, yet the explicit aim of quantitative easing was to support asset prices. Inflating asset prices on credit is deemed to be good for the economy, despite loading it down with debt. But public spending into the “real” economy, raising employment levels and sustaining consumer spending, is deemed bad – except when this is financed by personal borrowing from the banks. So in each case, increasing bank profits is the standard by which fiscal policy is to be judged!
The result is a policy asymmetry that is opposite from what most epochs have deemed fair or helpful to economic growth. Bankers and bondholders insist that the public sector borrow from them, blocking the government’s power to self-finance its operations – with one glaring exception. That exception occurs when the banks themselves need free money creation. The Fed provided nearly free credit to the banks under QE2, and Chairman Ben Bernanke promised to continue this policy until such time as the unemployment rate drops to 6.5%. The pretense is that low interest rates spur employment, but the most pressing aim is to provide easy credit to revive borrowing and bid asset prices back up.
Fiscal Deflation on Top of Debt Deflation
The main financial problem with funding war occurs after the return to normalcy, when creditors press for budget surpluses to roll back the public debt that has been run up. This imposes fiscal austerity, reducing wages and commodity prices relative to the debts that are owed. Consumer spending shrinks and prices decline as governments spend less, while higher taxes withdraw revenue. This is what is occurring in today’s financial war, much as it has in past military postwar returns to peace.
Governments have the power to resist this deflationary policy. Like commercial banks, they can create money on their computer keyboards. Indeed, since 2008 the government has created debt to support the Finance, Insurance and Real Estate (FIRE) sector more than the “real” production and consumption economy.
In contrast to public spending for goods and services (or social programs that increase market demand), most of the bank credit that led to the 2008 financial collapse was created to finance the purchase property already in place, stocks and bonds already issued, or companies already in existence. The effect has been to load down the economy with mortgages, bonds and bank debt whose carrying charges eat into spending on current output. The $13 trillion bank subsidy since 2008 (to enable banks to earn their way out of negative equity) brings us back to the question of why taxes should be levied on the 99% to pre-save for Social Security and Medicare, but not for the bank bailout.
Current tax policy encourages financial and rent extraction that has become the major economic problem of our epoch. Industrial productivity continues to rise, but debt is growing even more inexorably. Instead of fueling economic growth, this of credit/debt threatens to absorb the economic surplus, plunging the economy into austerity, debt deflation and negative equity.
So despite the fact that the financial system is broken, it has gained control over public policy to sustain and even obtain tax favoritism for a dysfunctional overgrowth of bank credit. Unlike the progress of science and technology, this debt is not part of nature. It is a social construct. The financial sector has politicized it by pressing to privatize economic rent rather than collect it as the tax base. This financialization of rent-extracting opportunities does not reflect a natural or inevitable evolution of “the market.” It is a capture of market structures and fiscal policy. Bank lobbyists have campaigned to shift the economic arena to the political sphere of lawmaking and tax policy, with side battlegrounds in the mass media and universities to capture the hearts and minds of voters to believe that the quickest and most efficient way to build up wealth is by bank credit and debt leverage.
Budget Deficits as an Antidote to Austerity
Public debts everywhere are growing, as taxes only cover part of public spending. The least costly way to finance this expenditure is to issue money – the paper currency and coins we carry in our pockets. Holders of this currency technically are creditors to the government – and to society, which accepts this money in payment. Yet despite being nominally a form of public debt, this money serves as public capital inasmuch as it is not normally expected to be repaid. This government money does not bear interest, and may be thought of as “equity capital” or “equity money,” and hence part of the economy’s net worth.
If taxes did fully cover government spending, there would be no budget deficit – or new public money creation. Government budget deficits pump money into the economy. Conversely, running a budget surplus retires the public debt or currency outstanding. This deflationary effect occurred in the late 19th-century, causing monetary deflation that plunged the U.S. economy into depression. Likewise when President Bill Clinton ran a budget surplus late in his administration, the economy relied on commercial banks to supply credit to use as the means of payment, charging interest for this service. As Stephanie Kelton summarizes this historical experience:
The federal government has achieved fiscal balance (even surpluses) in just seven periods since 1776, bringing in enough revenue to cover all of its spending during 1817-21, 1823-36, 1852-57, 1867-73, 1880-93, 1920-30 and 1998-2001. We have also experienced six depressions. They began in 1819, 1837, 1857, 1873, 1893 and 1929.
Do you see the correlation? The one exception to this pattern occurred in the late 1990s and early 2000s, when the dot-com and housing bubbles fueled a consumption binge that delayed the harmful effects of the Clinton surpluses until the Great Recession of 2007-09.
When taxpayers pay more to the government than the economy receives in public spending, the effect is like paying banks more than they provide in new credit. The debt volume is reduced (increasing the reported savings rate). The resulting austerity is favorable to the financial sector but harmful to the rest of the economy.
Most people think of money as a pure asset (like a coin or a $10 dollar bill), not as being simultaneously a public debt. But to an accountant, a balance sheet always balances: Assets = Liabilities + Net Worth. This liability-side ambivalence is confusing to most people. It takes some time to think in terms of offsetting assets and liabilities as mirror images of each other. Much as cosmologists assume that the universe is symmetrical – with positively charged matter having an anti-matter counterpart somewhere at the other end – so accountants view the money in our pocket as being created by the government’s deficit spending. Holders of the Federal Reserve’s paper currency technically can redeem it, but they will simply get paid in other denominations of the same currency.
The word “redeem” comes from settling debts. This was the purpose for which money first came into being. Governments redeem money by accepting it for tax payment. In addition to issuing paper currency, the Federal Reserve injects money into the economy by writing checks electronically. The recipients (usually banks selling Treasury bonds or, more recently, packages of mortgage loans) gain a deposit at the central bank. This is the kind of deposit that was created by the above-mentioned $13 trillion in new debt that the government turned over to Wall Street after the September 2008 crisis. The price impact was felt in financial asset markets, not in prices for goods and services or labor’s wages.
This Federal Reserve and Treasury credit was not counted as part of the government’s operating deficit. Yet it increased public debt, without being spent on “real” GDP. The banks used this money mainly to gamble on foreign exchange and interest-rate arbitrage as noted above, to buy smaller banks (helping make themselves Too Big To Fail), and to keep paying their managers high salaries and bonuses.
This monetization of debt shows how different government budgets are from family budgets. Individuals must save to pay for retirement or other spending. They cannot print their own money, or tax others. But governments do not need to “save” (or tax) to pay for their spending. Their ability to create money means that they do not need to save in advance to pay for wars, Social Security or other needs.
Keynesian Deficit Spending vs. Bailing out Wall Street to Keep the Debt Overhead in Place
There are two kinds of markets: hiring labor to produce goods and services in the “real” economy, and transactions in financial assets and property claims in the FIRE sector. Governments can run budget deficits by financing either of these two spheres. Since President Franklin Roosevelt’s WPA programs in the 1930s, along with his public infrastructure investment in roads, dams and other construction – and military arms spending after World War II broke out – “Keynesian” spending on goods and services has been used to hire labor or pay for social programs. This pumps money into the economy via the GDP-type transactions that appear in the National Income and Product Accounts. It is not inflationary when unemployment exists.
However, the debt that characterized the Paulson-Geithner bailout of Wall Street was created not to spend on goods and services, but to buy (or take liability for) mortgages and bank loans, insurance default bets and arbitrage gambles. The aim was to subsidize financial losses while keeping the debt overhead in place, so that banks and other financial institutions could “earn their way” out of negative net worth, at the economy’s expense. The idea was that they could start lending again to prevent real estate prices from falling further, saving them from having to write down their debt claims to bring levels back down within the ability to be paid.
The Ideological Crisis Underlying Today’s Tax and Financial Policy
From antiquity and for thousands of years, land, natural resources and monopolies, seaports and roads were kept in the public domain. In more recent times railroads, subway lines, airlines, and gas and electric utilities were made public. The aim was to provide their basic services at cost or at subsidized prices rather than letting them be privatized into rent-extracting opportunities. The Progressive Era capped this transition to a more equitable economy by enacting progressive income and wealth taxes.
Economies were liberating themselves from the special privileges that European feudalism and colonialism had granted to favored insiders. The aim of ending these privileges – or taxing away economic rent where it occurs naturally, as in the land’s site value and natural resource rent – was to lower the costs of living and doing business. This was expected to make progressive economies more competitive, obliging other countries to follow suit or be rendered obsolete. The era of what was considered to be socialism in one form or another seemed to be at hand – rising role of the public sector as part and parcel of the evolution of technology and prosperity.
But the landowning and financial classes fought back, seeking to expunge the central policy conclusion of classical economics: the doctrine that free-lunch economic rent should serve as the tax base for economies seeking to be most efficient and fair. Imbued with academic legitimacy by the University of Chicago (which Upton Sinclair aptly named the University of Standard Oil) the new post-classical economics has adopted Milton Friedman’s motto: “There Is No Such Thing As A Free Lunch” (TINSTAAFL). If it is not seen, it has less likelihood of being taxed.
The political problem faced by rentiers – the “idle rich” siphoning off most of the economy’s gains for themselves – is to convince voters to agree that labor and consumers should be taxed rather than the financial gains of the wealthiest 1%. How long can they defer people from seeing that making interest tax-exempt pushes the government’s budget further into deficit? To free financial wealth and asset-price gains from taxes – while blocking the government from financing its deficits by its own public option for money creation – the academics sponsored by financial lobbyists hijacked monetary theory, fiscal policy and economic theory in general. On seeming grounds of efficiency they claimed that government no longer should regulate Wall Street and its corporate clients. Instead of criticizing rent seeking as in earlier centuries, they depicted government as an oppressive Leviathan for using its power to protect markets from monopolies, crooked drug companies, health insurance companies and predatory finance.
This idea that a “free market” is one free for Wall Street to act without regulation can be popularized only by censoring the history of economic thought. It would not do for people to read what Adam Smith and subsequent economists actually taught about rent, taxes and the need for regulation or public ownership. Academic economics is turned into an Orwellian exercise in doublethink, designed to convince the population that the bottom 99% should pay taxes rather than the 1% that obtain most interest, dividends and capital gains. By denying that a free lunch exists, and by confusing the relationship between money and taxes, they have turned the economics discipline and much political discourse into a lobbying effort for the 1%.
Lobbyists for the 1% frame the fiscal question in terms of “How can we make the 99% pay for their own social programs?” The implicit follow-up is, “so that we (the 1%) don’t have to pay?” This is how the Social Security system came to be “funded” and then “underfunded.” The most regressive tax of all is the FICA payroll tax at 15.3% of wages up to about $105,000. Above that, the rich don’t have to contribute. This payroll tax exceeds the income tax paid by many blue-collar families. The pretense is that not taxing these free lunchers will make economies more competitive and pull them out of depression. The reality is the opposite: Instead of taxing the wealthy on their free lunch, the tax burden raises the cost of living and doing business. This is a major reason why the U.S. economy is being de-industrialized today.
The key question is what the 1% do with their revenue “freed” from taxes. The answer is that they lend it out to indebt the 99%. This polarizes the economy between creditors and debtors. Over the past generation the wealthiest 1% have rewritten the tax laws to a point where they now receive an estimated 66% – two thirds – of all returns to wealth (interest, dividends, rents and capital gains), and a reported 93% of all income gains since the Wall Street bailout of September 2008.
They have used this money to finance the election campaigns of politicians committed to shifting taxes onto the 99%. They also have bought control of the major news media that shape peoples’ understanding of what is happening. And as Thorstein Veblen described nearly a century ago, businessmen have become the heads most universities and directed their curriculum along “business friendly” lines.
The clearest way to analyze any financial system is to ask Who/Whom. That is because financial systems are basically a set of debts owed to creditors. In today’s neo-rentier economy the bottom 99% (labor and consumers) owe the 1% (bondholders, stockholders and property owners). Corporate business and government bodies also are indebted to this 1%. The degree of financial polarization has sharply accelerated as the 1% are making their move to indebt the 99% – along with industry, state, local and federal government – to the point where the entire economic surplus is owed as debt service. The aim is to monopolize the economy, above all the money-creating privilege of supplying the credit that the economy needs to grow and transact business, enabling them to extract interest and other fees for this privilege.
The top 1% have nearly succeeded in siphoning off the entire surplus for themselves, receiving 93% of U.S. income growth since September 2008. Their control over the political process has enabled them to use each new financial crisis to strengthen their position by forcing companies, states and localities to relinquish property to creditors and financial investors. So after monopolizing the economic surplus, they now are seeking to transfer to themselves the economic infrastructure, land and natural resources, and any other asset on which a rent-extracting tollbooth can be placed.
The situation is akin to that of medieval Europe in the wake of the Nordic invasions. The supra-national force of Rome in feudal times is now situated in Washington, with Christianity replaced by the Washington Consensus wielded via the IMF, World Bank, WTO and its satellite institutions such as the European Central Bank, backed by the moral and ideological role academic economists rather than the Church. And on the new financial battlefield, Wall Street underwriters have used the crisis as an opportunity to press for privatization. Chicago’s strong Democratic political machine sold rights to install parking meters on its sidewalks, and has tried to turn its public roads into privatized toll roads. And the city’s Mayor Rahm Emanuel has used privatization of its airport services to break labor unionization, Thatcher-style. The class war is back in business, with financial tactics playing a leading role barely anticipated a century ago.
This monopolization of property is what Europe’s medieval military conquests sought to achieve, and what its colonization of foreign continents replicated. But whereas it achieved this originally by military conquest of the land, today’s 1% do it l by financializing the economy (although the military arm of force is not absent, to be sure, as the world saw in Chile after 1973).
The financial quandary confronting us
The economy’s debt overhead has grown so large that not everyone can be paid. Rising default rates pose the question age-old question of Who/Whom. The answer almost always is that big fish eat little fish. Big banks (too big to fail) are eating little banks, while the 1% try to take the lion’s share for themselves by annulling public and corporate debts owed to the 99%. Their plan is to downgrade Social Security and Medicare savings to “entitlements,” as if it is a matter of sound fiscal choice not to pay low-income payers whilerentiers at the top re-christen themselves “job creators,” as if they have made their gains by helping wage-earners rather than waging war against them.
The problem is not Social Security, which can be paid out of normal tax revenue, as in Germany’s pay-as-you-go system. This fiscal problem – untaxing real estate, oil and gas, natural resources, monopolies and the banks – has been depicted as financial – as if one needs to save in advance by a special tax to lend to the government to cut taxes on the 99%.
The real pension cliff is with corporate, state and local pension plans, which are being underfunded and looted by financial managers. The shortfall is getting worse as the downturn reduces local tax revenues, leaving states and cities unable to fund their programs, to invest in new public infrastructure, or even to maintain and repair existing investments. Public transportation in particular is suffering, raising user fees to riders in order to pay bondholders. But it is mainly retirees who are being told to sacrifice. (The sanctimonious verb is “share” in the sacrifice, although this evidently does not apply to the 1%.)
The bank lobby would like the economy to keep trying to borrow its way out of debt and thus dig itself deeper into a financial hole that puts yet more private and public property at risk of default and foreclosure. The idea is for the government to “stabilize” the financial system by bailing out the banks – that is, doing for them what it has not been willing to do for recipients of Social Security and Medicare, or for states and localities no longer receiving revenue sharing, or for homeowners in negative equity suffering from exploding interest rates even while bank borrowing costs from the Fed have plunged. The dream is that the happy Greenspan financial bubble can be recovered, making everyone rich again, if only they will debt-leverage to bid up real estate, stock and bond prices and create new capital gains.
Realizing this dream is the only way that pension funds can pay retirees. They will be insolvent if they cannot make their scheduled 8+%, giving new meaning to the term “fictitious capital.” And in the real estate market, prices will not soar again until speculators jump back in as they did prior to 2008. If student loans are not annulled, graduates face a lifetime of indentured servitude. But that is how much of colonial America was settled, after all – working off the price of their liberty, only to be plunged into the cauldron of vast real estate speculations and fortunes-by-theft on which the Republic was founded (or at least the greatest American fortunes). It was imagined that such bondage belonged only to a bygone era, not to the future of the West. But we may now look back to that era for a snapshot of our future.
The financial plan is for the government is to supply nearly free credit to the banks, so that they can to lend debtors enough – at the widest interest-rate markups in recent memory (what banks charge borrowers and credit-card users over their less-than-1% borrowing costs) – to pay down the debts that were run up before 2008.
This is not a program to increase market demand for the products of labor. It is not the kind of circular flow that economists have described as the essence of industrial capitalism. It is a financial rake-off of a magnitude such as has not existed since medieval European times, and the last stifling days of the oligarchic Roman Empire two thousand years ago.
Imagining that an economy can be grounded on these policies will further destabilize the economy rather than alleviate today’s debt deflation. But if the economy is saved, the banks cannot be. This is why the Obama Administration has chosen to save the banks, not the economy. The Fed’s prime directive is to keep interest rates low – to revive lending not to finance new business investment to produce more, but simply to inflate the asset prices that back the bank loans that constitute bank reserves. It is the convoluted dream of a new Bubble Economy – or more accurately a new Great Giveaway.
Here’s the quandary: If the Fed keeps interest rates low, how are corporate, state and local pension plans to make the 8+% returns needed to pay their scheduled pensions? Are they to gamble more with hedge funds playing Casino Capitalism?
On the other hand, if interest rates rise, this will reduce the capitalization multiple at which banks lend against current rental income and profits. Higher interest rates will lower prices for real estate, corporate stocks and bonds, pushing the banks (and pension funds) even deeper into negative equity.
So something has to give. Either way, the financial system cannot continue along its present path. Only debt write-offs will “free” markets to resume spending on goods and services. And only a shift of taxes onto rent-yielding property and tollbooths, finance and monopolies will save prices from being loaded down with extractive overhead charges and refocus lending to finance production and employment. Unless this is done, there is no way the U.S. economy can become competitive in international markets, except of course for military hardware and intellectual property rights for escapist cultural artifacts.
The solution for Social Security, Medicare and Medicaid is to de-financialize them. Treat them like government programs for military spending, beachfront rebuilding and bank subsidies, and pay their costs out of current tax revenue and new money creation by central banks doing what they were founded to do.
Politicians shy away from confronting this solution mainly because the financial sector has sponsored a tunnel vision that ignores the role of debt, money, and the phenomena of economic rent, debt leverage and asset-price inflation that have become the defining characteristics of today’s financial crisis. Government policy has been captured to try and save – or at least subsidize – a financial system that cannot be saved more than temporarily. It is being kept on life support at the cost of shrinking the economy – while true medical spending for real life support is being cut back for much of the population.
The economy is dying from a financial respiratory disease, or what the Physiocrats would have called a circulatory disorder. Instead of freeing the economy from debt, income is being diverted to pay credit card debt and mortgage debts. Students without jobs remain burdened with over $1 trillion of student debt, with the time-honored safety valve of bankruptcy closed off to them. Many graduates must live with their parents as marriage rates and family formation (and hence, new house-buying) decline. The economy is dying. That is what neoliberalism does.
Now that the debt build-up has run its course, the banking sector has put its hope in gambling on mathematical probabilities via hedge fund capitalism. This Casino Capitalist has become the stage of finance capitalism following Pension Fund capitalism – and preceding the insolvency stage of austerity and property seizures.
The open question now is whether neofeudalism will be the end stage. Austerity deepens rather than cures public budget deficits. Unlike past centuries, these deficits are not being incurred to wage war, but to pay a financial system that has become predatory on the “real” economy of production and consumption. The collapse of this system is what caused today’s budget deficit. Instead of recognizing this, the Obama Administration is trying to make labor pay. Pushing wage-earners over the “fiscal cliff” to make them pay for Wall Street’s financial bailout (sanctimoniously calling their taxes “user fees”) can only shrink of market more, pushing the economy into a fatal combination of tax-ridden and debt-ridden fiscal and financial austerity.
The whistling in the intellectual dark that central bankers call by the technocratic term “deleveraging” (paying off the debts that have been run up) means diverting yet more income to pay the financial sector. This is antithetical to resuming economic growth and restoring employment levels. The recent lesson of European experience is that despite austerity, debt has risen from 381% of GDP in mid-2007 to 417% in mid—2012. That is what happens when economies shrink: debts mount up at arrears (and with stiff financial penalties).
But even as economies shrink, the financial sector enriches itself by turning its debt claims – what 19th-century economists called “fictitious capital” before it was called finance capital – into a property grab. This makes an unrealistic debt overhead – unrealistic because there is no way that it can be paid under existing property relations and income distribution – into a living nightmare. That is what is happening in Europe, and it is the aim of Obama Administration of Tim Geithner, Ben Bernanke, Erik Holder et al. They would make America look like Europe, wracked by rising unemployment, falling markets and the related syndrome of adverse social and political consequences of the financial warfare waged against labor, industry and government together. The alternative to the road to serfdom – governments strong enough to protect populations against predatory finance – turns out to be a detour along the road to debt peonage and neofeudalism.
So we are experiencing the end of a myth, or at least the end of an Orwellian rhetorical patter talk about what free markets really are. They are not free if they are to pay rent-extractors rather than producers to cover the actual costs of production. Financial markets are not free if fraudsters are not punished for writing fictitious junk mortgages and paying ratings agencies to sell “opinions” that their clients’ predatory finance is sound wealth creation. A free market needs to be regulated from fraud and from rent seeking.
The other myth is that it is inflationary for central banks to monetize public spending. What increases prices is building interest and debt service, economic rent and financial charges into the cost of living and doing business. Debt-leveraging the price of housing, education and health care to make wage-earners pay over two-thirds of their income to the FIRE sector, FICA wage withholding and other taxes falling on labor are responsible for de-industrializing the economy and making it uncompetitive.
Central bank money creation is not inflationary if it funds new production and employment. But that is not what is happening today. Monetary policy has been hijacked to inflate asset prices, or at least to stem their decline, or simply to give to the banks to gamble. “The economy” is less and less the sphere of production, consumption and employment; it is more and more a sphere of credit creation to buy assets, turning profits and income into interest payments until the entire economic surplus and repertory of property is pledged for debt service.
To celebrate this as a “postindustrial society” as if it is a new kind of universe in which everyone can get rich on debt leveraging is a deception. The road leading into this trap has been baited with billions of dollars of subsidized junk economics to entice voters to act against their interests. The post-classical pro-rentier financial narrative is false – intentionally so. The purpose of its economic model is to make people see the world and act (or invest their money) in a way so that its backers can make money off the people who follow the illusion being subsidized. It remains the task of a new economics to revive the classical distinction between wealth and overhead, earned and unearned income, profit and rentier income – and ultimately between capitalism and feudalism.
Notes.
[1] No such benefits were given to homeowners
whose real estate fell into negative equity. For the few who received
debt write-downs to current market value, the credit was treated as
normal income and taxed!
[2] Philip Aldrick, “Loss of
income caused by banks as bad as a ‘world war’, says BoE’s Andrew
Haldane,” The Telegraph, December 3, 2012. Mr. Haldane is the Bank’s
executive director for financial stability.